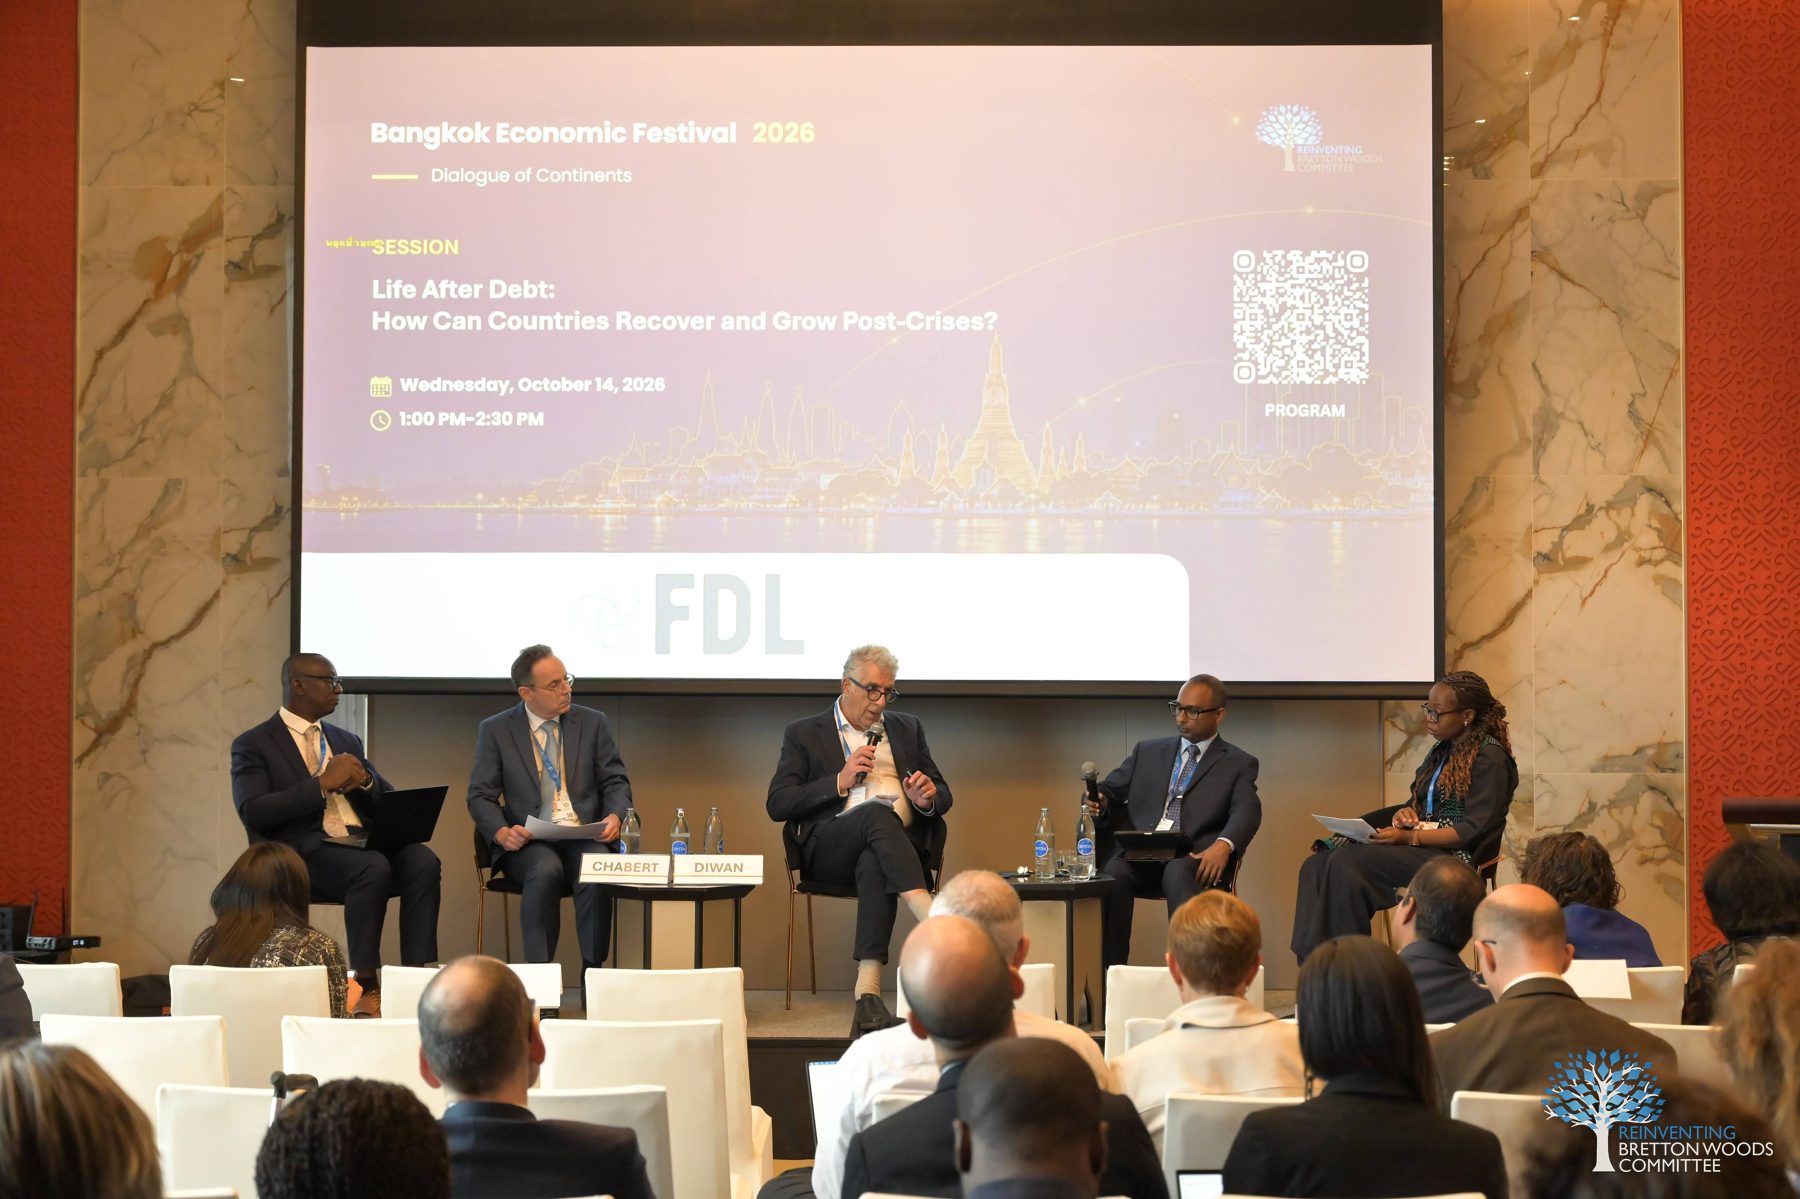
How Can Countries Recover and Grow Post-Crises?
Once debt restructuring is achieved, what comes next? Stabilizing a distressed economy is necessary, but it cannot be the end goal: a path built only to maximize repayments in the short term leaves countries exposed to the next shock, starves investment and medium-term growth, and strains social support. Moving from stabilization to recovery requires the deliberate provision of fiscal space, new money and, above all, trust and coordination among the country in recovery, its creditors, and multilateral lenders. The IMF program, underpinned by a macroeconomic framework and conditionalities, is where that common ground is forged.
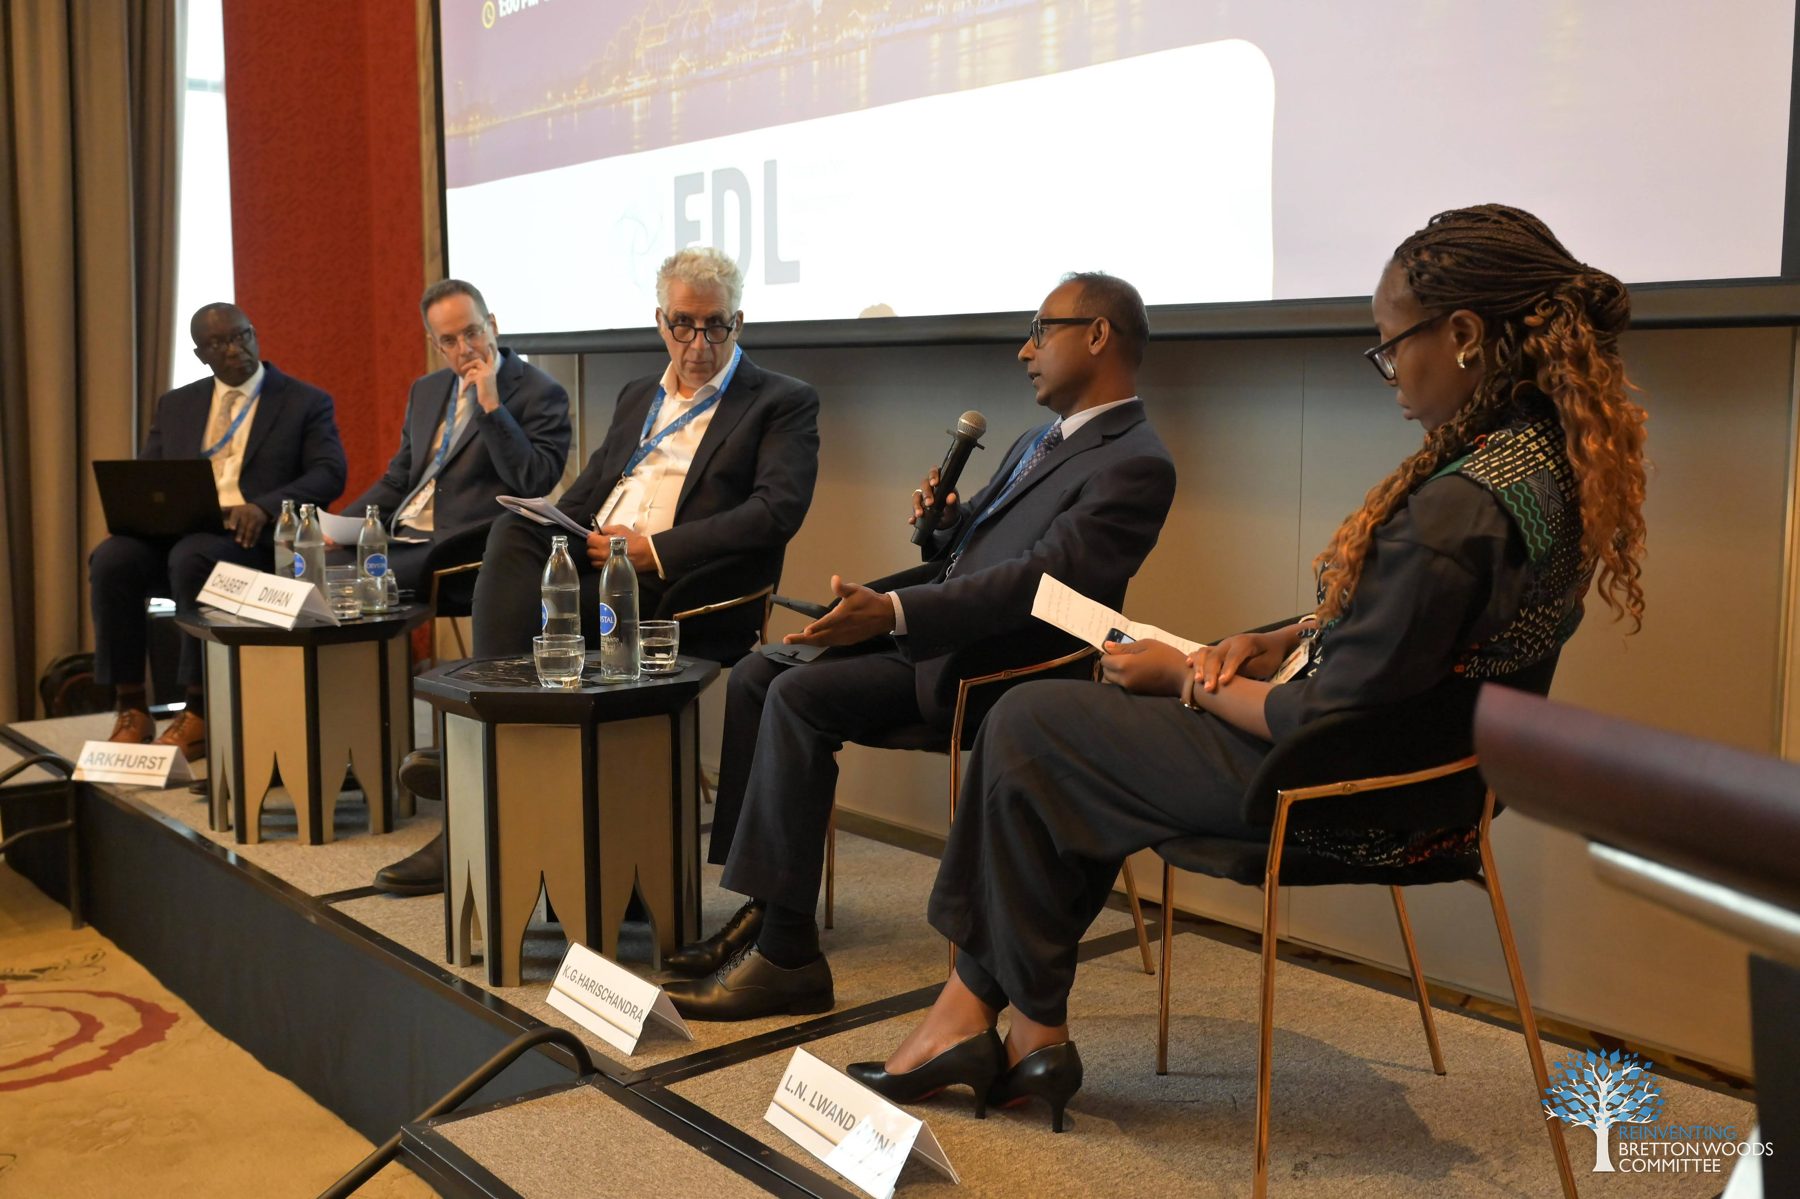
Despite well-known critiques, at least some recent debt restructuring cases seem to have remained more focused on stabilization than long-term development. The session will explore how countries that have recently undergone debt restructuring have fared and how policymakers can devise more pro-development strategies.
Chair
Ishac Diwan Research Director, FDL
Eyob Tekalign Governor, National Bank of Ethiopia
Mélina London Senior Economist, FDL
Masood Ahmed President Emeritus, Center for Global Development (CGDev)
Samuel Arkhurst Coordinating Director, Ministry of Finance of Ghana
Guillaume Chabert Deputy Director, Strategy, Policy and Review Department, International Monetary Fund
P. K. G. Harischandra Assistant Governor, Central Bank of Sri Lanka; Secretary to the Monetary Policy Board
Maryann L.N. Lwandamina Assistant Director, Debt Policy and Strategy, Ministry of Finance of Zambia
Mark Suzman CEO, Gates Foundation
The ultimate measure of successful debt restructuring is not simply how much debt is reduced or rescheduled. It's whether countries emerge with the capacity to invest, grow, create jobs, and finance their development sustainably.
The low trust equilibrium is everybody does just the minimum amount needed to get to the stabilization phase. And that's a perfectly rational response in a low trust model.
We need to address these debt vulnerabilities as early as possible without delaying the adjustment. Because Sri Lanka announced the debt standstill at the very last moment because we were almost running out of our external buffers and the market access was really restricted.
Debt crises come in the context of a broader crisis in general, right? So the focus on stabilization is just right because you have to go fast, you have to stabilize the economy because otherwise you will never have a recovery.
We can get the math right on paper, while leaving the countries without enough room to invest and grow. A country can exit default while its people are still living through the crisis. And this is a fact. That cannot be our definition of success.
What's important for you to remember is that the debt reduction path is only as solid as the growth assumption. But when we look at the main pillars for this growth, we don't see in the programs strong pillars or strong reasons for this growth to happen.
You stabilize on your flow indicators, but the stock remains a little bit stagnant. So it's through debt for development and other such swaps where you can now start to eat away at that stock.