Reinventing Bretton Woods CommitteeBangkok Economic Festival
Back to the week

Global Macro Sessions

Date
Thursday 15 October
Time
08:00 to 16:30
Venue
Valia Hotel, Bangkok

Session partners

UBSThe SEACEN Centre

Overview

The IMF and World Bank Annual Meetings return to Bangkok for the first time since 1991, a year that marked the apparent triumph of convergence, the expansion of global trade, and the beginning of Asia’s extraordinary economic transformation. Thirty-five years later, the world that gathered in Bangkok in 1991 is barely recognizable. The assumptions that markets would converge, institutions would strengthen, and growth would be shared have been tested by the global financial crisis, the pandemic, and a new wave of geopolitical fragmentation that challenges the foundations of the multilateral order.

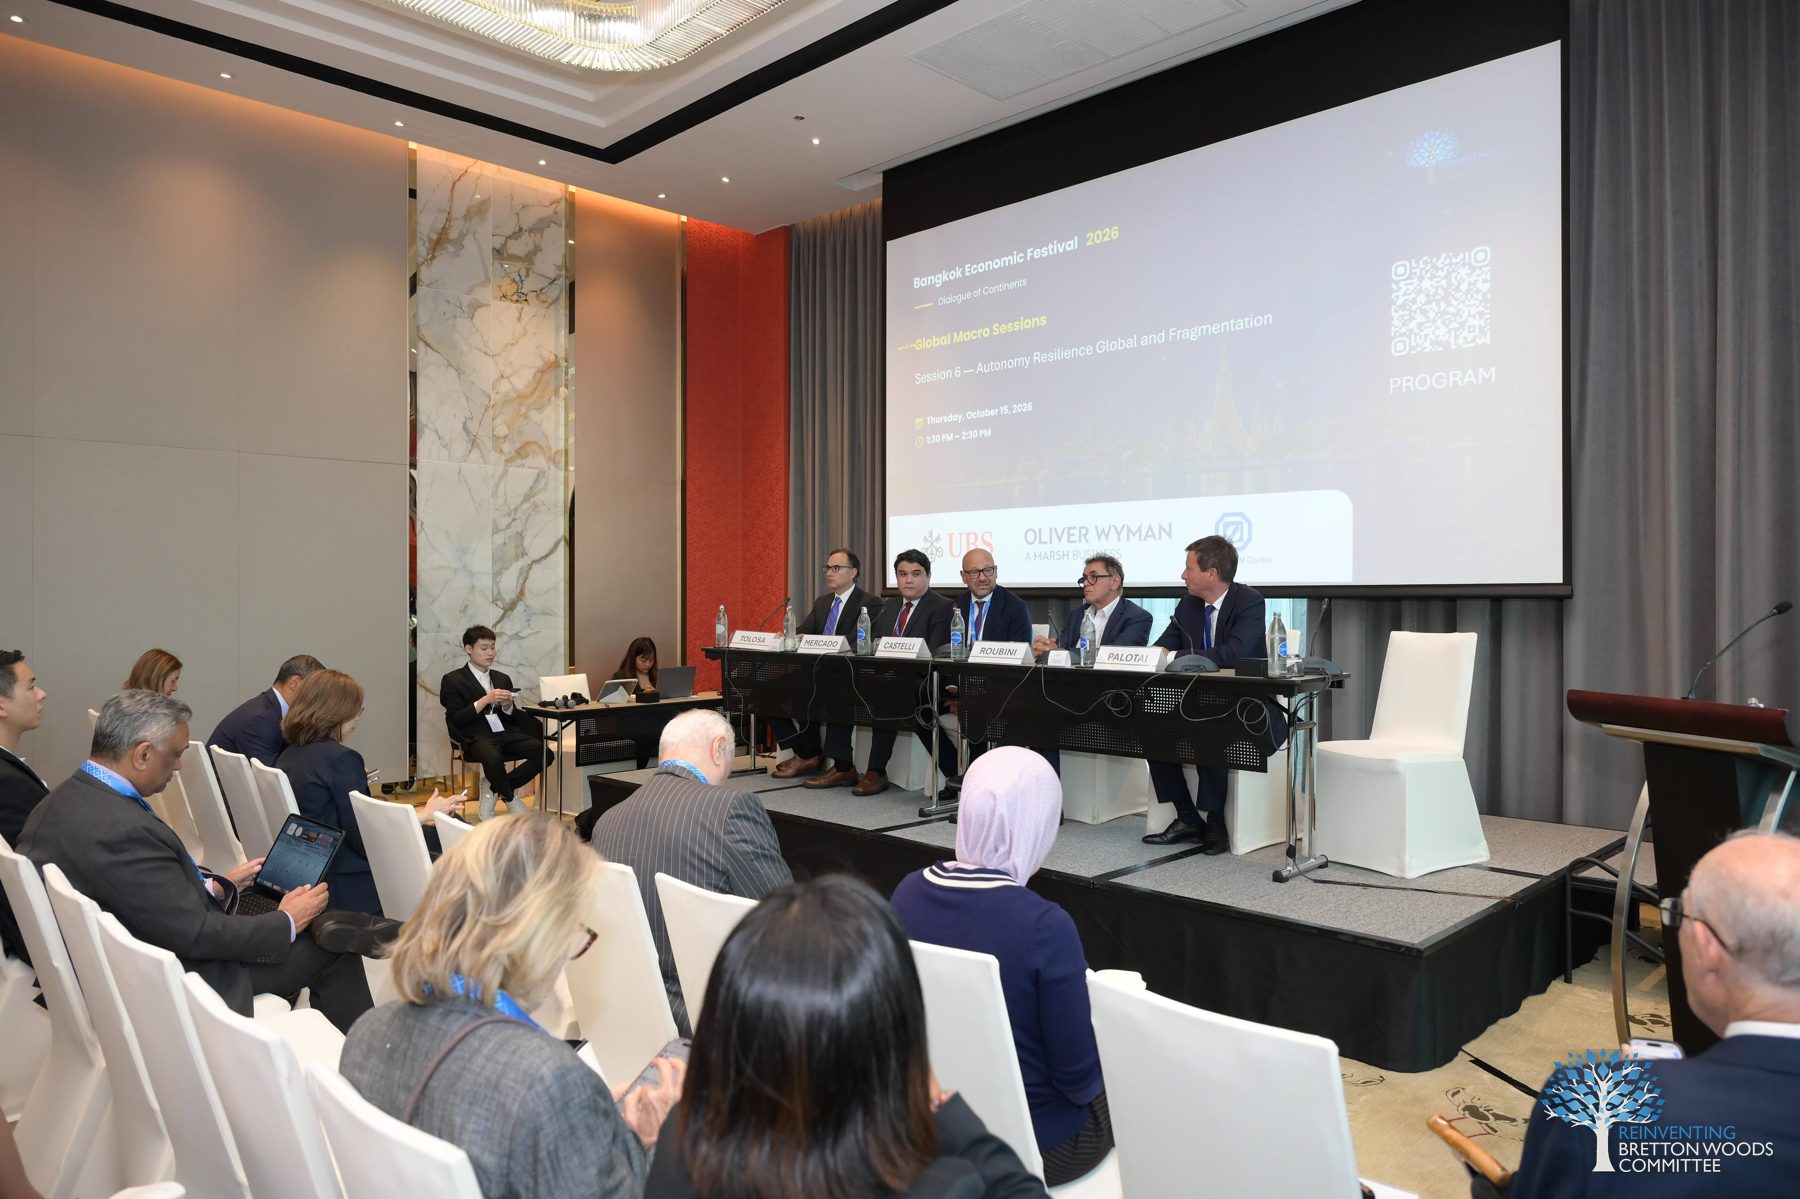
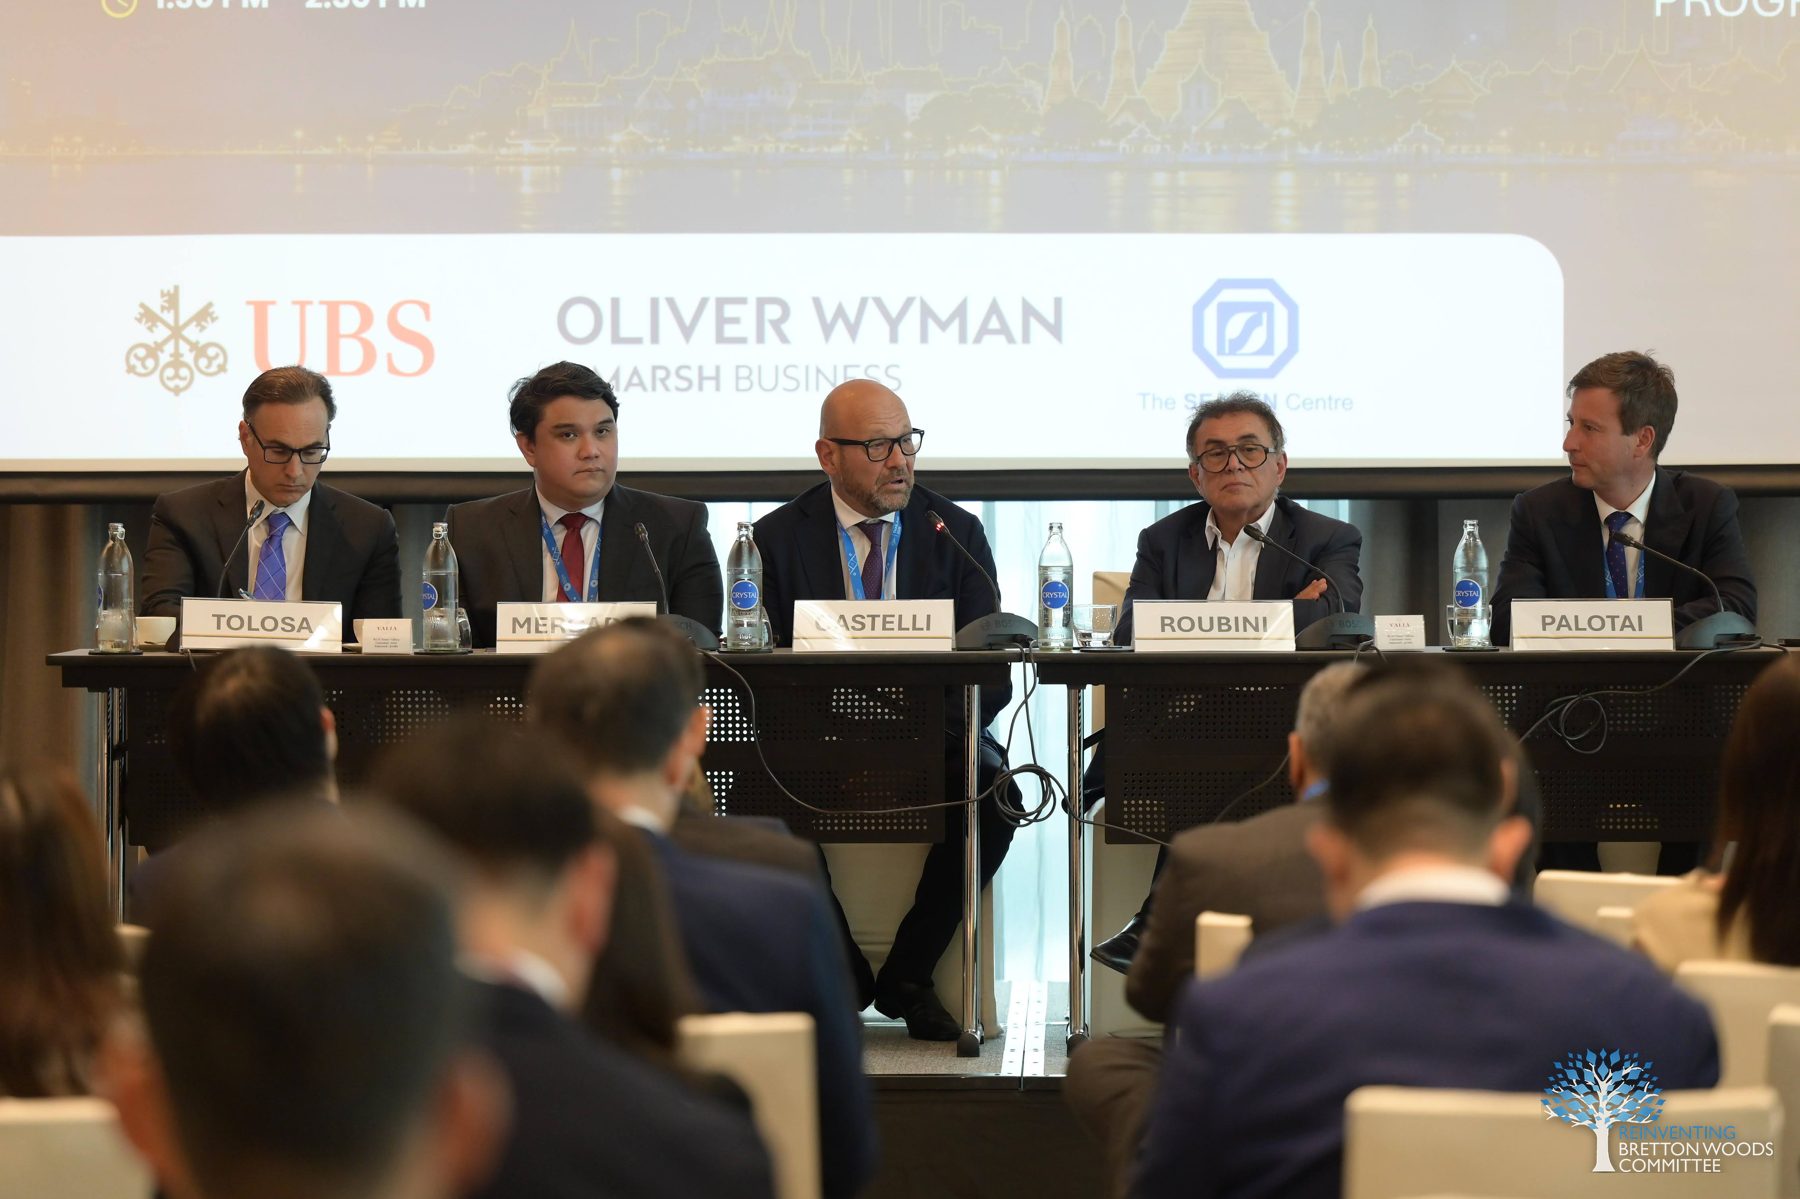
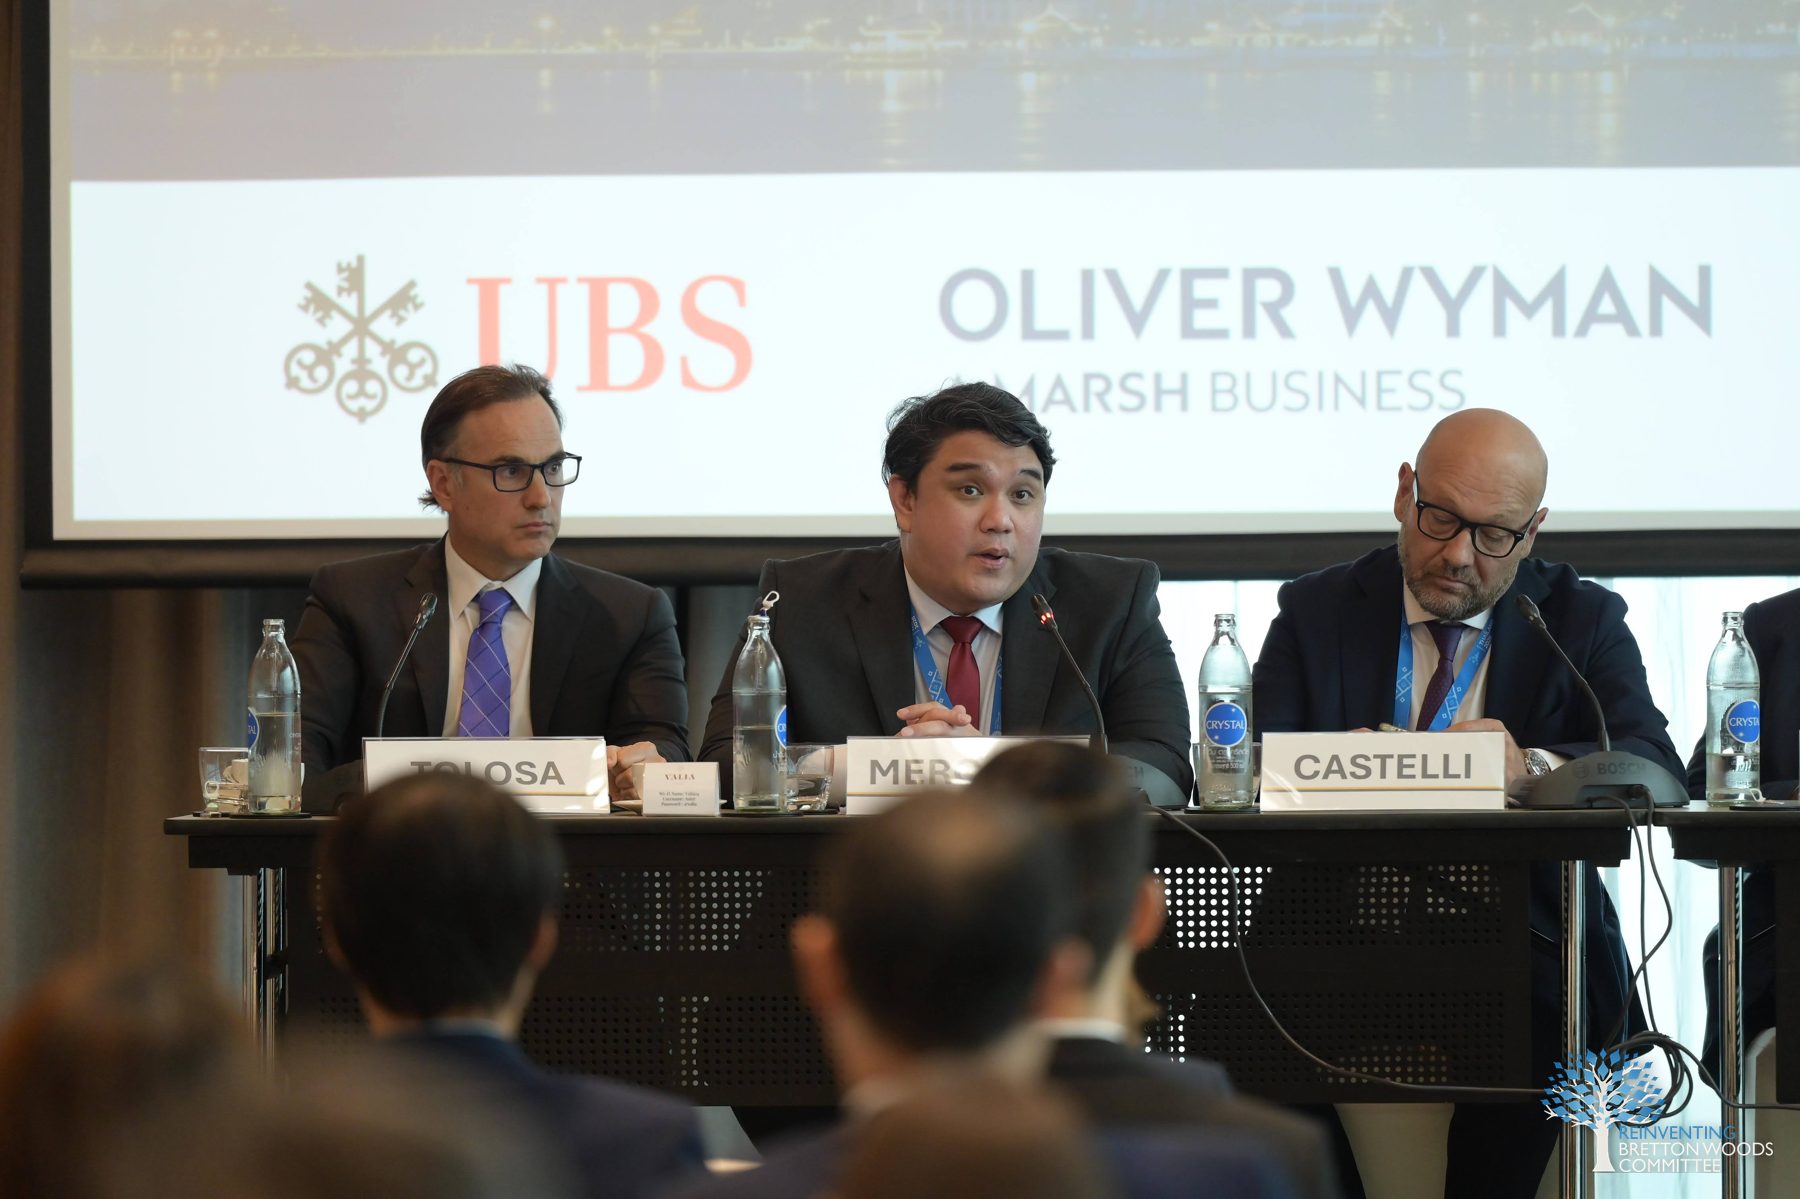
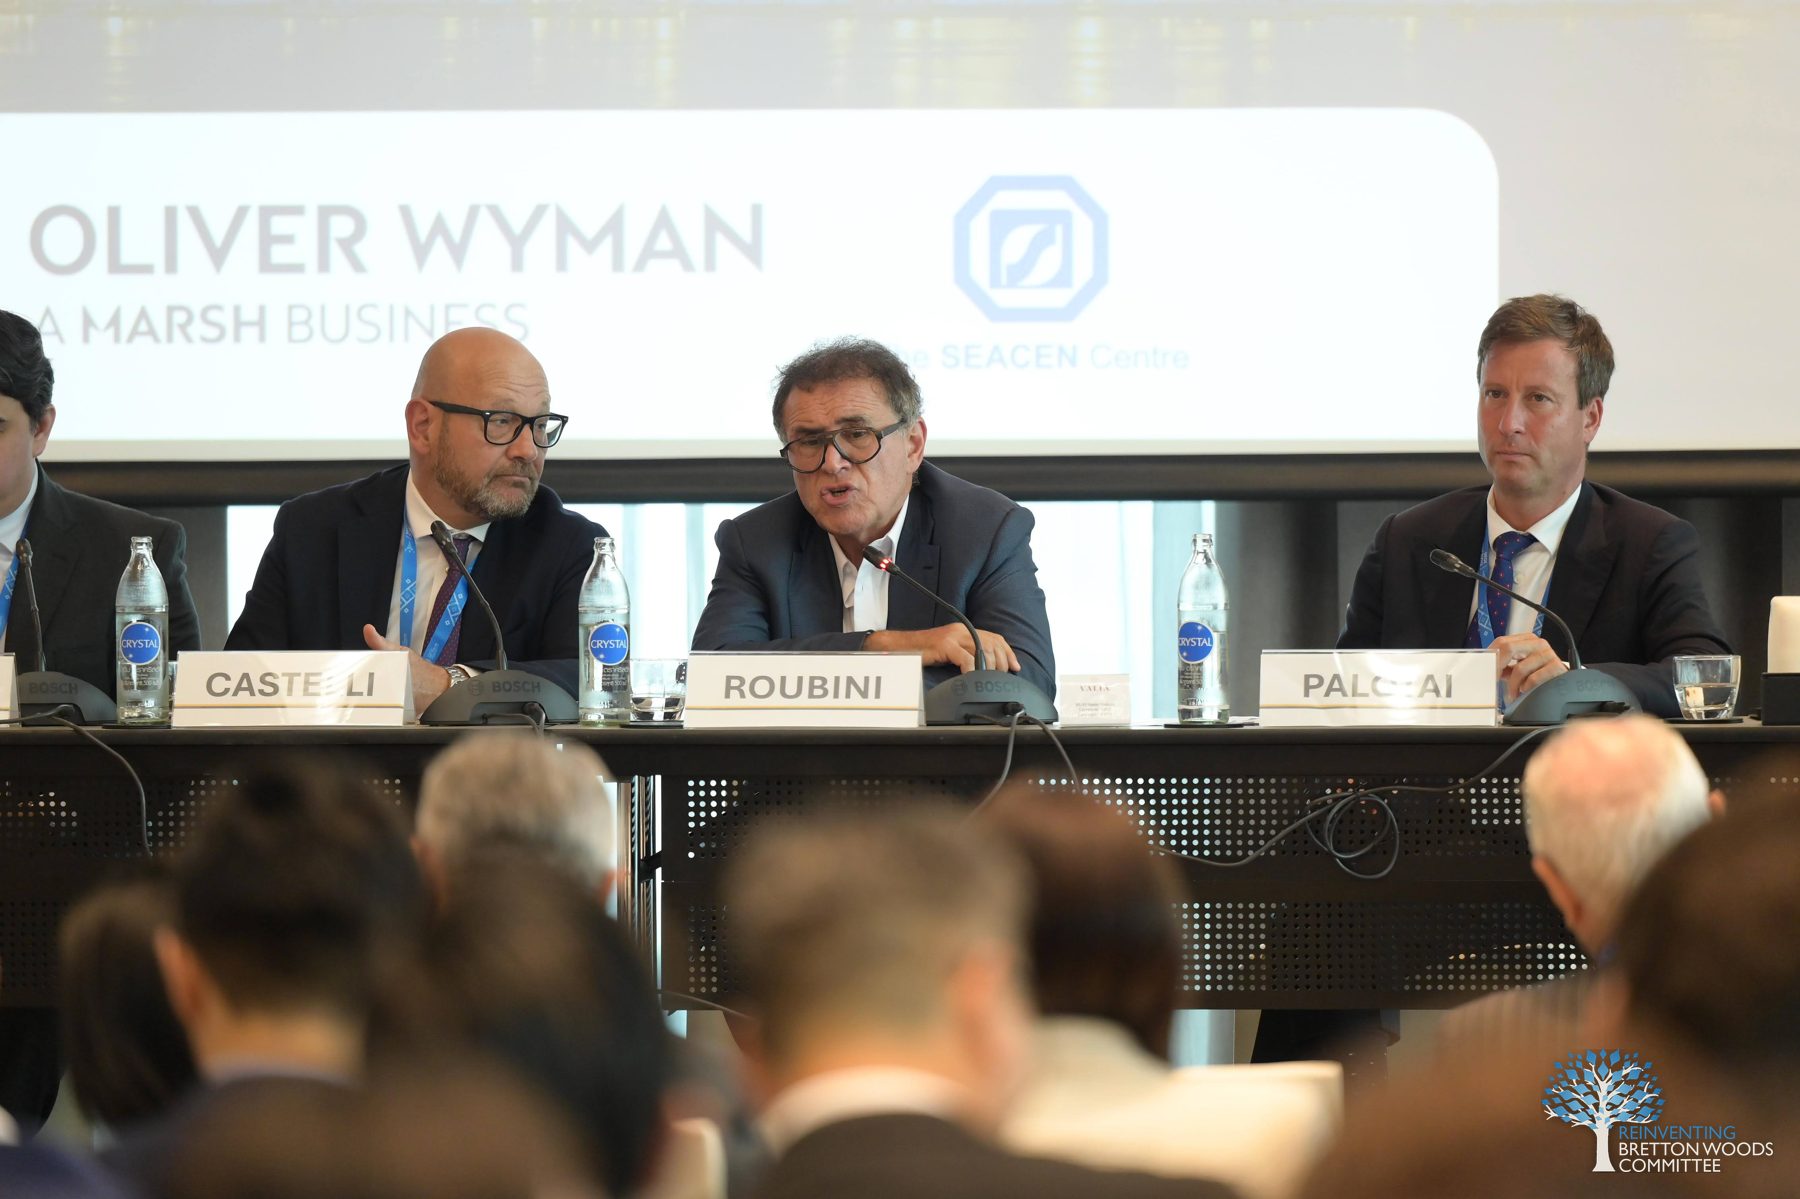
Against this backdrop, the Global Macro programme steps back from daily data and market noise to examine the monetary and financial order now taking shape. It brings together central bankers, economists, policy leaders, and market experts to consider the forces shaping global growth, the rethinking of monetary policy in a shock-prone world, and the consequences of fragmentation for financial stability and economic governance.

The programme also focuses on monetary sovereignty and emerging-market resilience. Discussions will address digital money and stablecoins, de-dollarisation, capital-flow and commodity volatility, China’s evolving economic model, and the renewed controversy over global imbalances. Across the day, participants will ask whether institutions designed for an integrated global economy can adapt to a more fragmented and contested international system.

Guiding Questions

  • What is driving the global economy in 2026, and is the AI investment wave a genuine productivity shift?
  • How is the U.S. Federal Reserve navigating heightened global uncertainty, and what will its policy and regulatory choices mean internationally?
  • How should monetary-policy frameworks evolve in a world of more frequent supply shocks?
  • What opportunities and risks do stablecoins and new cross-border settlement rails create, and how can economies preserve monetary sovereignty?
  • How can emerging economies in Asia and Latin America defend policy autonomy and financial resilience amid fragmentation, high debt, and volatile capital flows?
  • Are current developments pointing toward meaningful de-dollarisation?
  • How are China’s domestic-demand, monetary, fiscal, trade, and investment dynamics changing, and what do they imply for global growth?
  • How should policymakers understand and respond to renewed global imbalances?

Michelle W. Bowman, Federal Reserve

Session Programme

  1. Registration and Welcome Breakfast

  2. Opening remarks

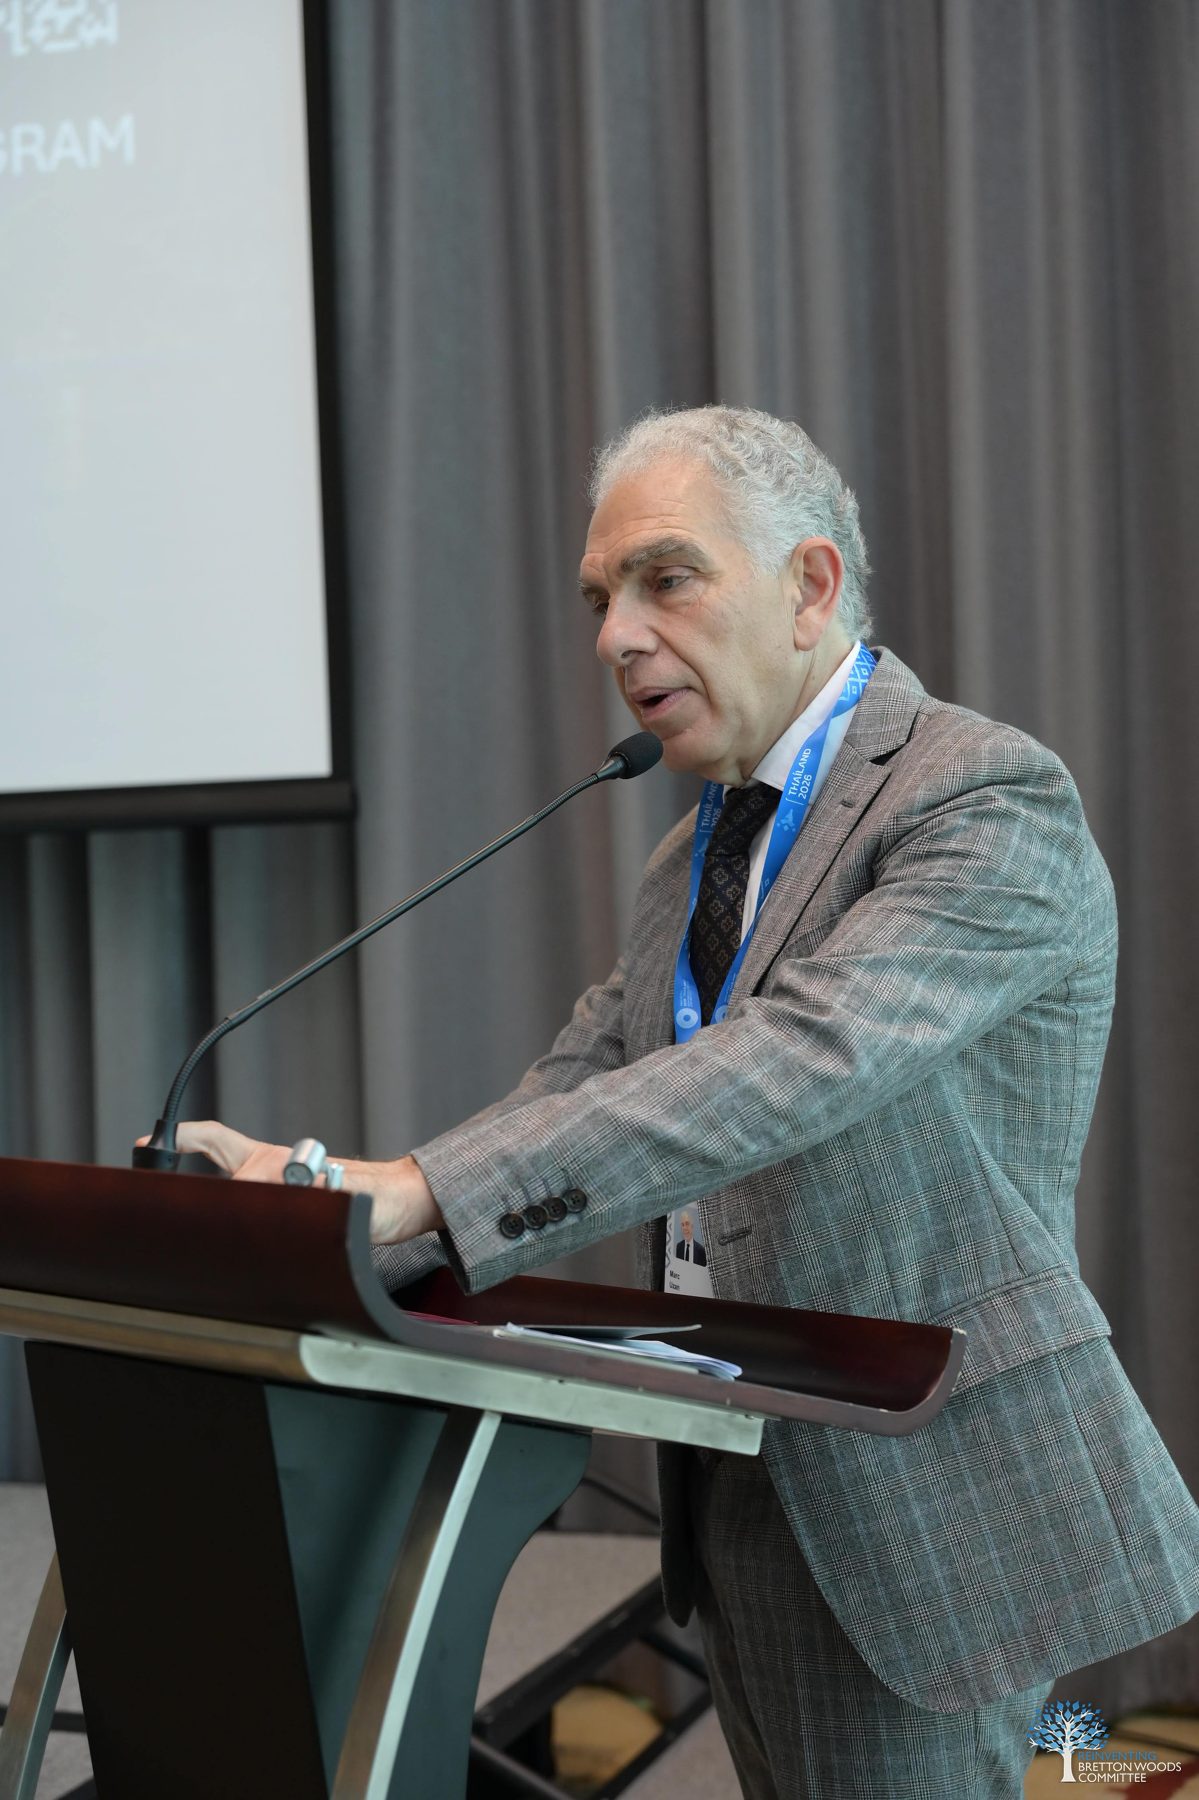
    Marc Uzan Executive Director, Reinventing Bretton Woods Committee

  3. Section I: The global economy
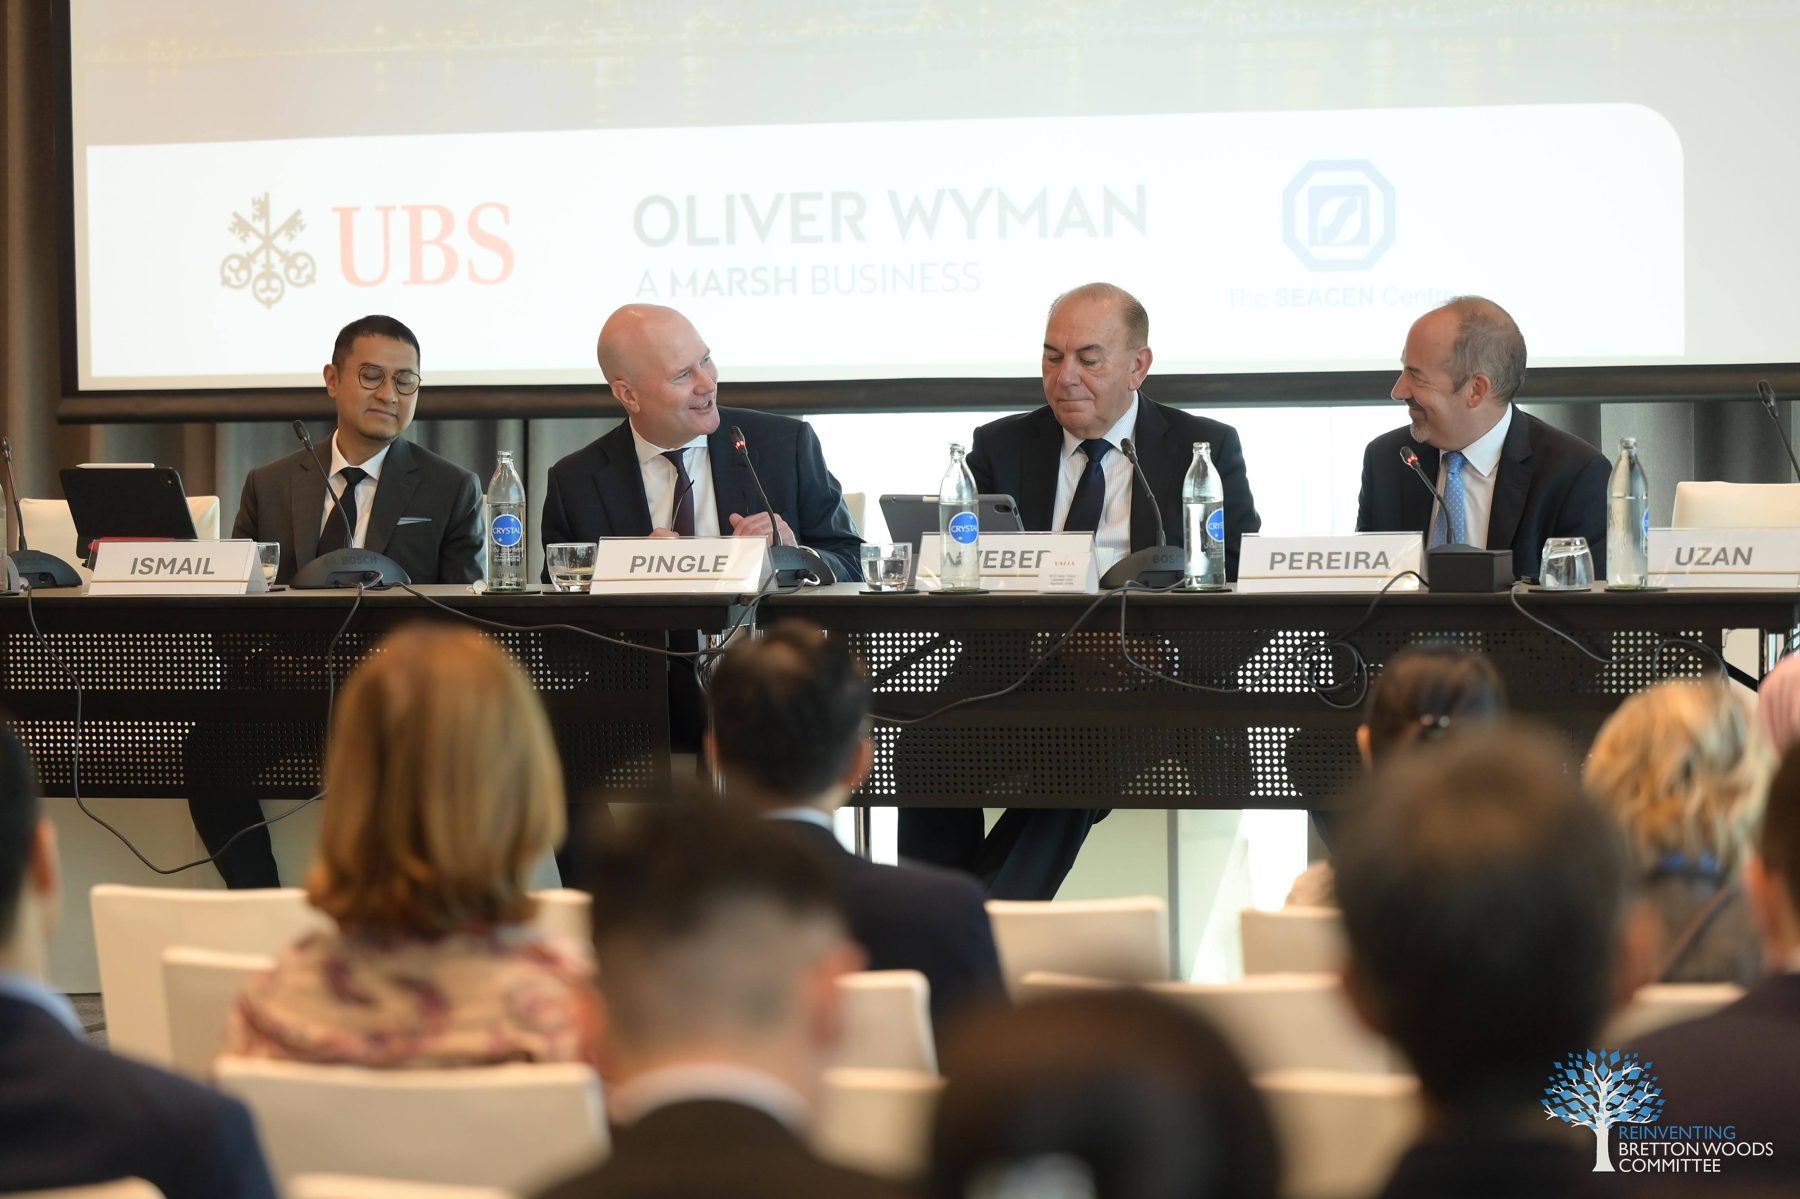
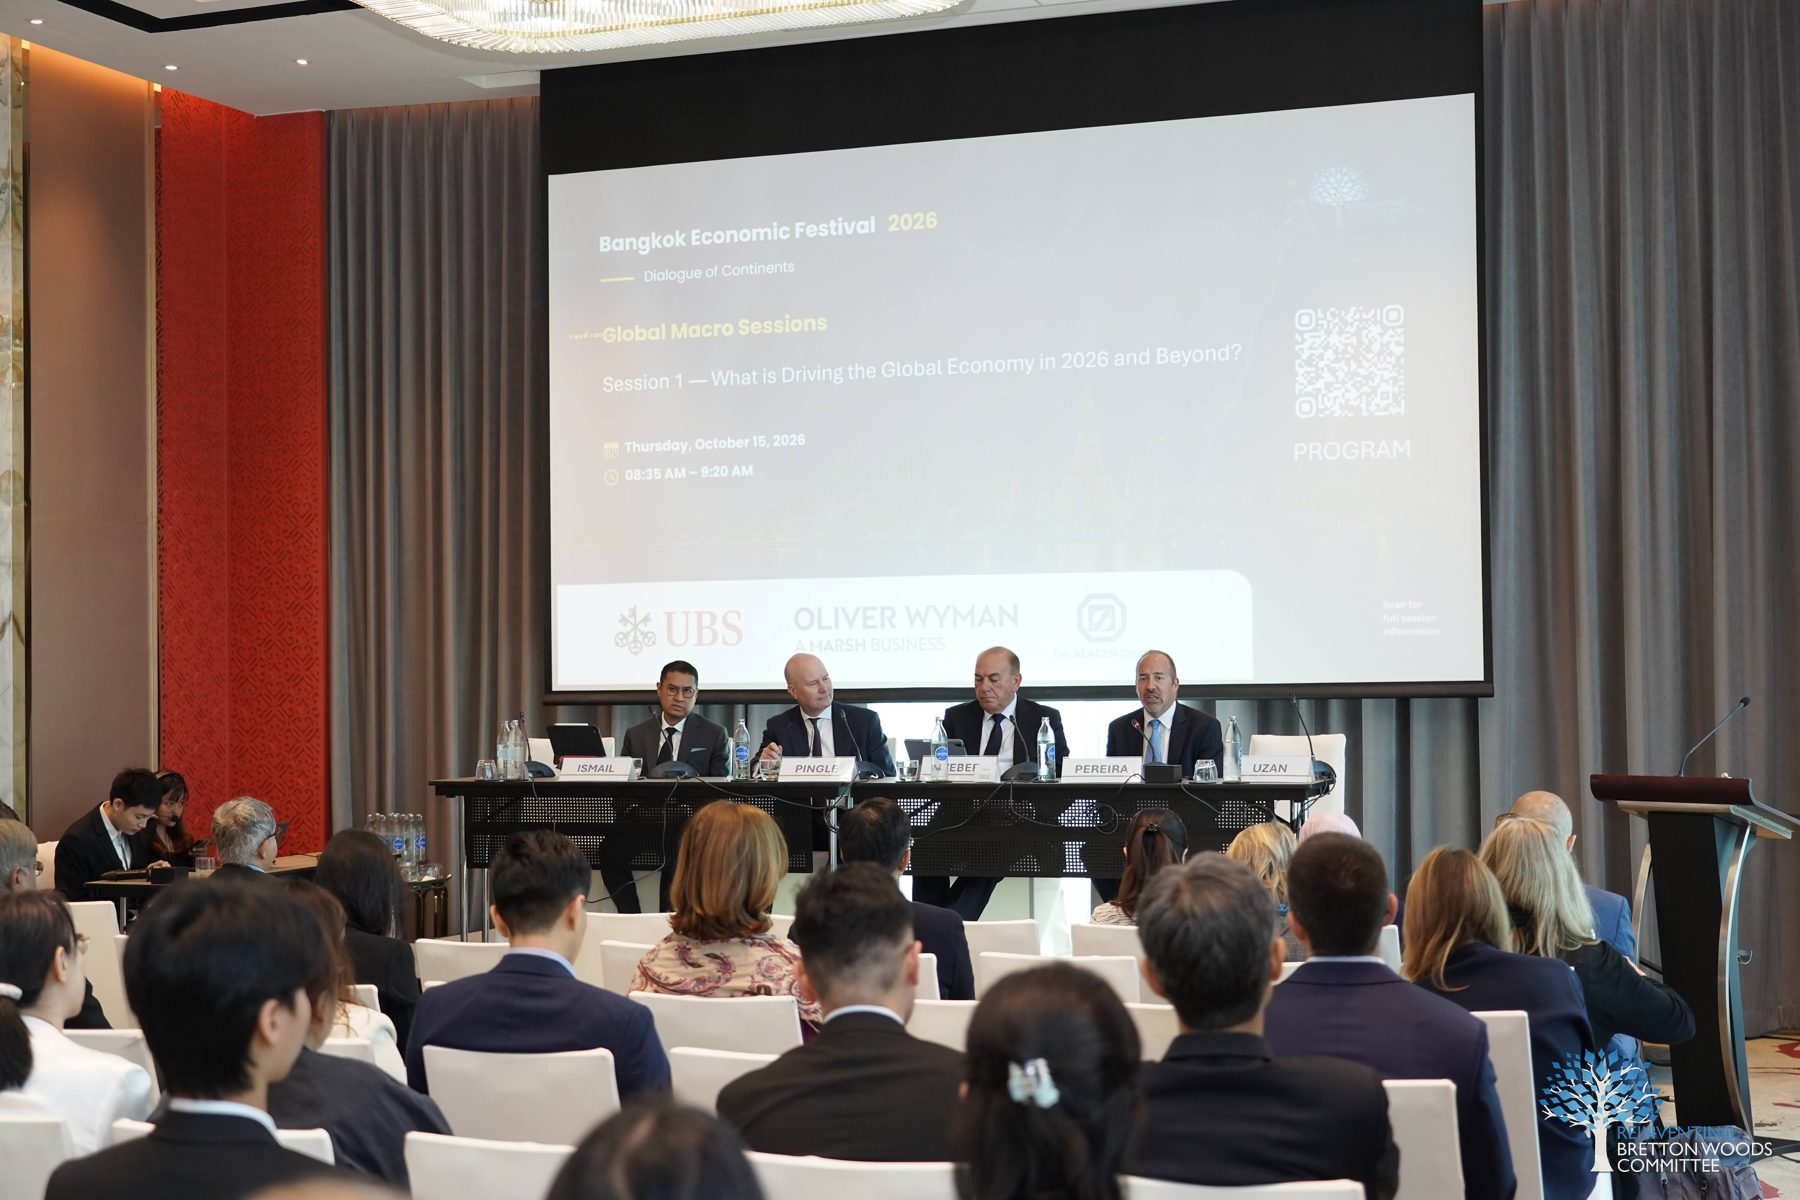
  4. Session 1 — What is Driving the Global Economy in 2026 and Beyond?

    Axel Weber President, Center for Financial Studies

    Fraziali Ismail Assistant Governor, Central Bank of Malaysia

    Álvaro Santos Pereira Governor, Central Bank of Portugal

    Jonathan Pingle US Chief Economist, UBS (chair)

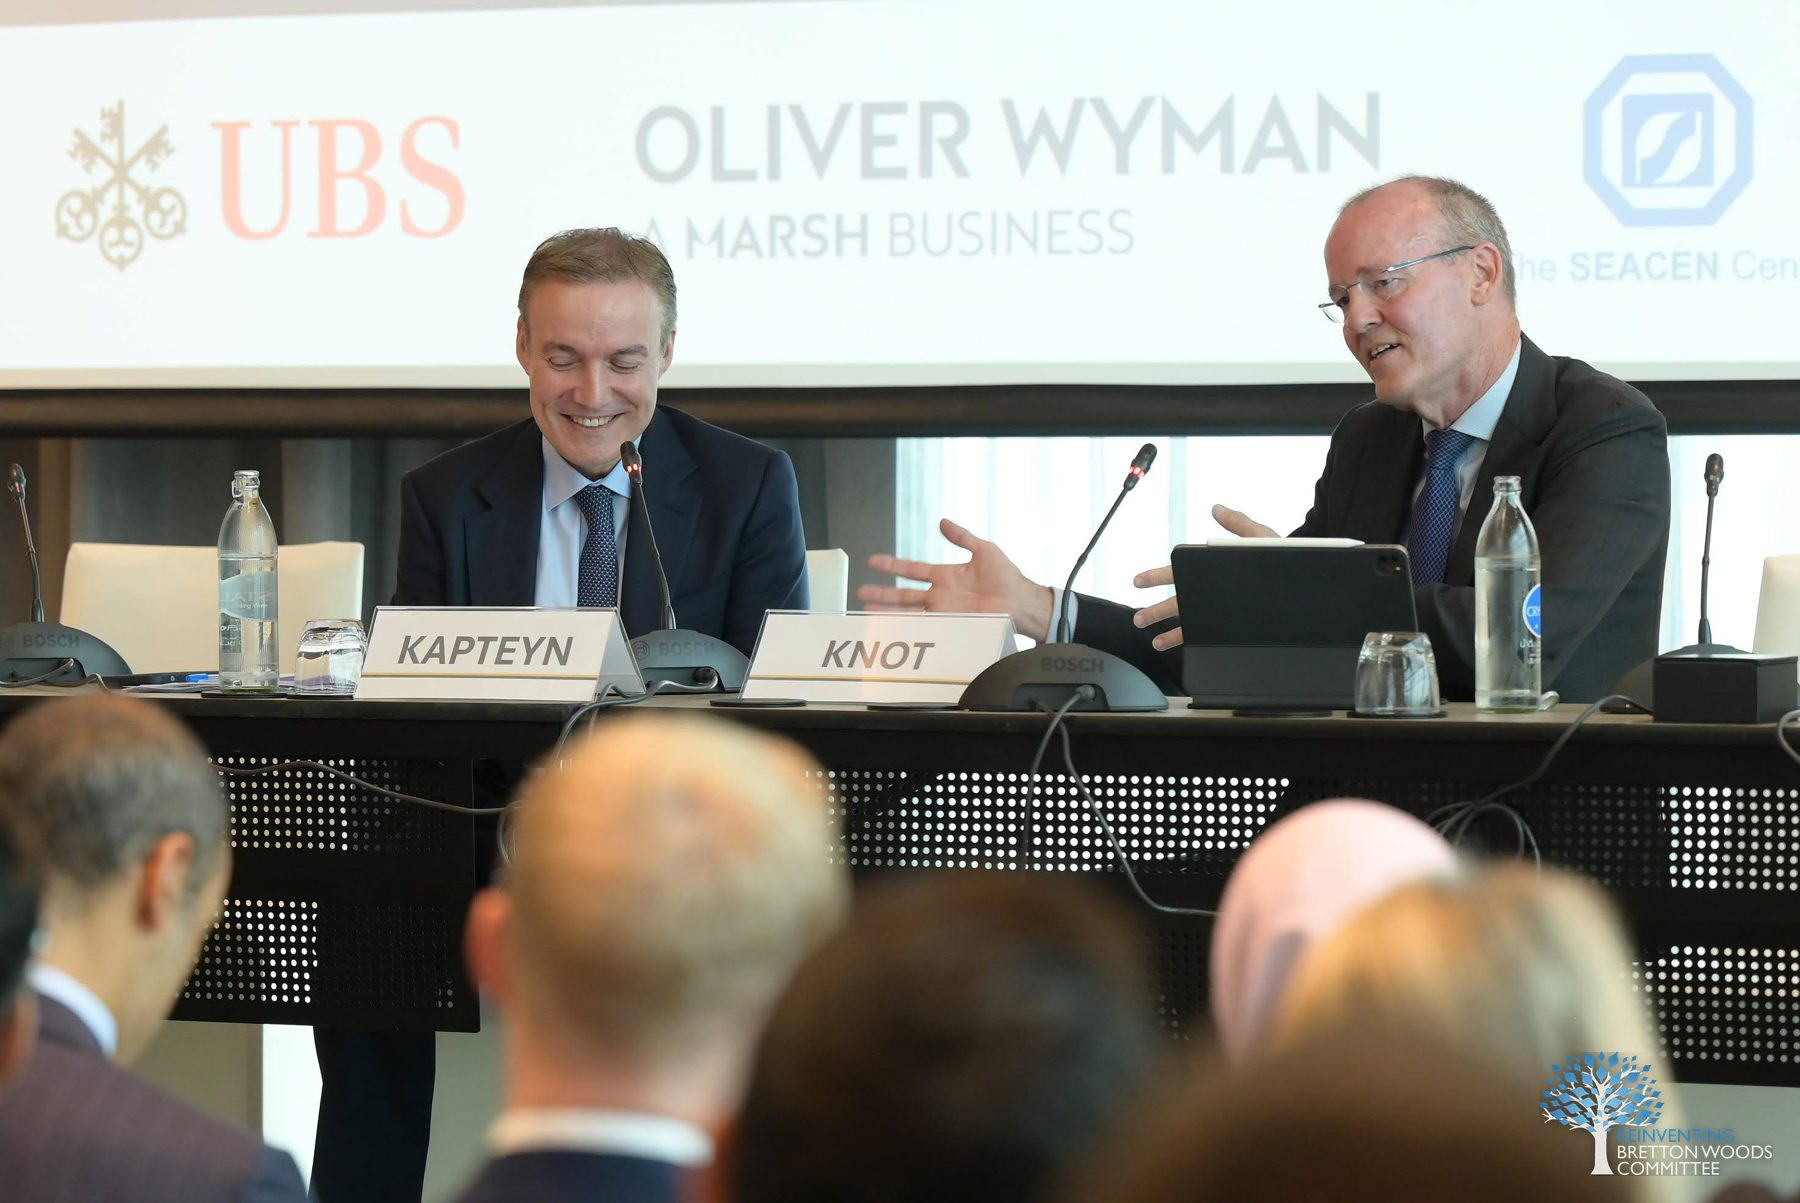
  5. Session 2 — Fireside: In Conversation with Klaas Knot

    Klaas Knot Former Chair, Financial Stability Board; Former President, De Nederlandsche Bank; Distinguished Visiting Fellow, PIIE

    Arend Kapteyn Global Chief Economist, UBS

    (Chair)

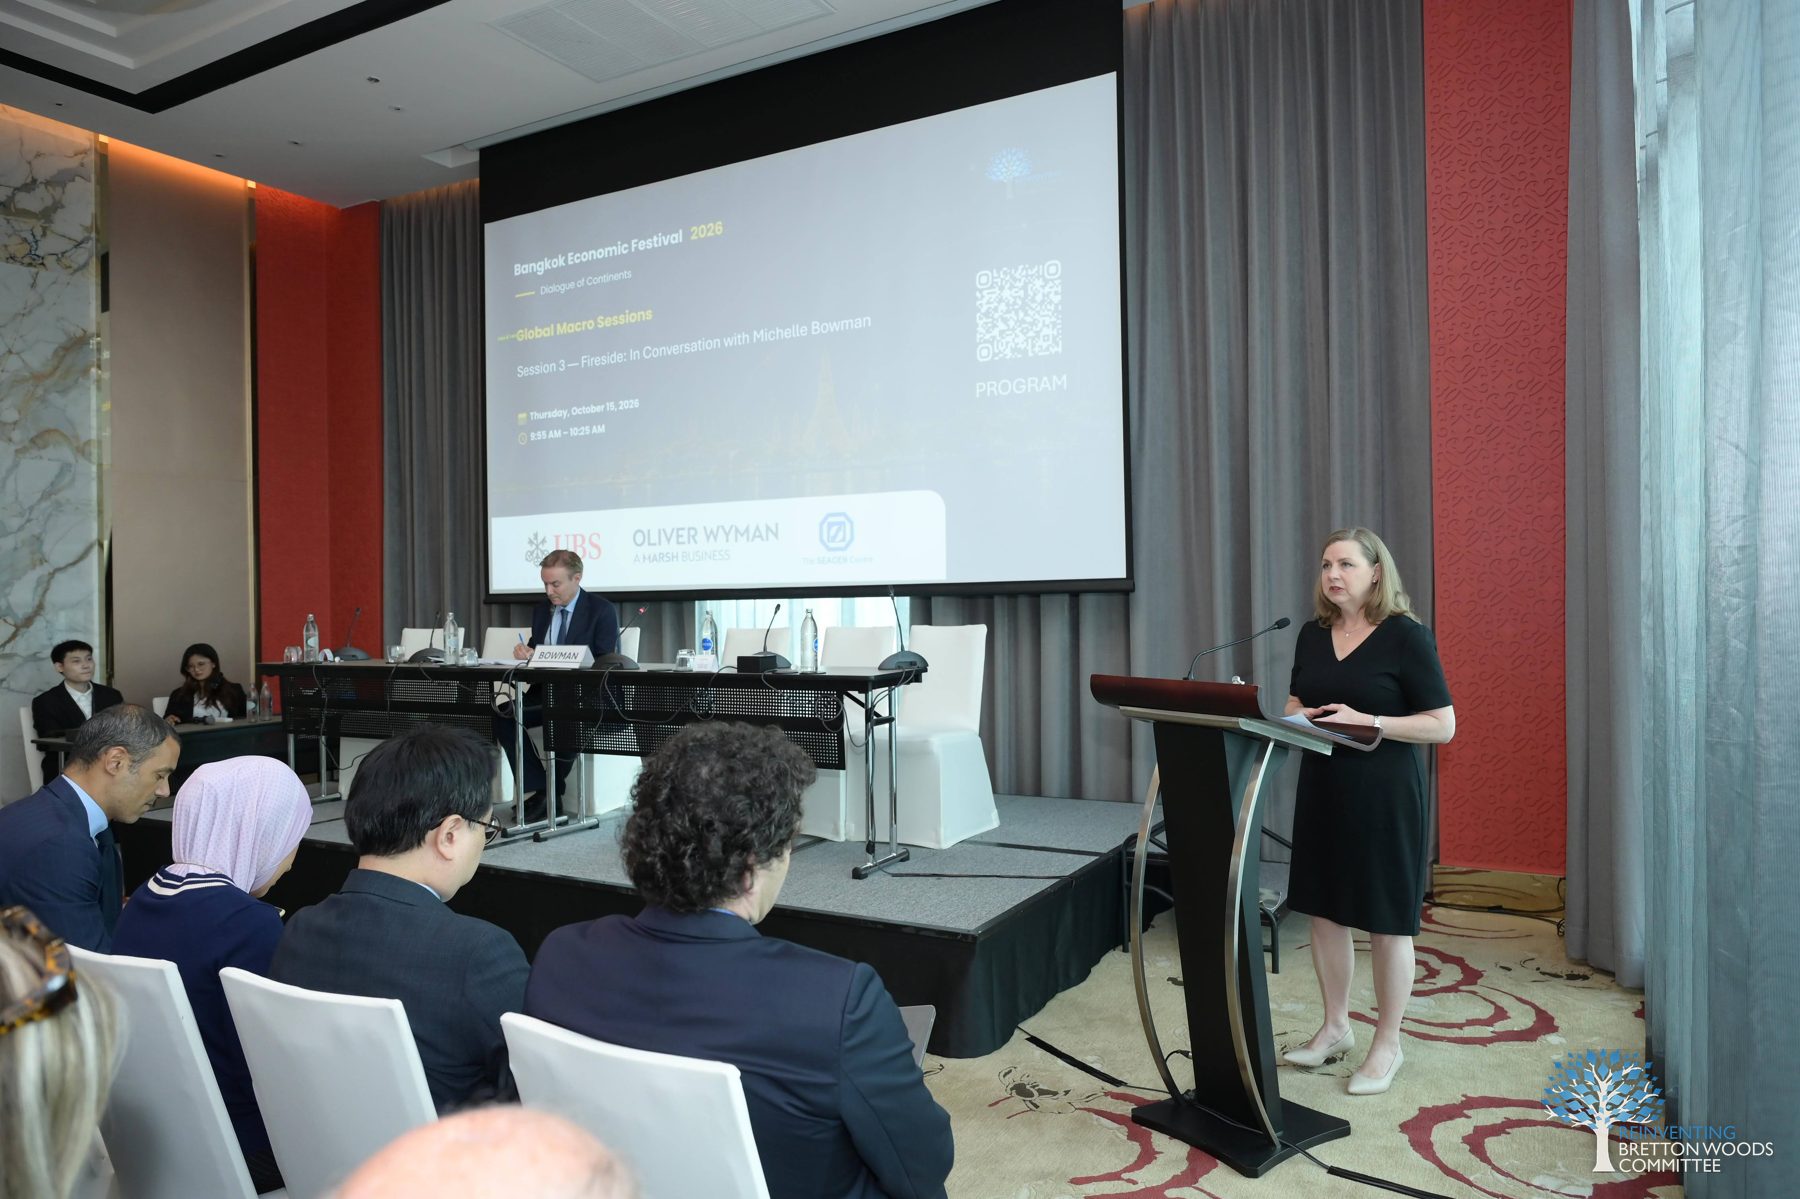
  6. Session 3 — Fireside: In Conversation with Michelle Bowman

    Michelle W. Bowman Vice Chair for Supervision, Federal Reserve; Chair, FSB Standing Committee on Supervisory and Regulatory Cooperation

  7. Coffee Break

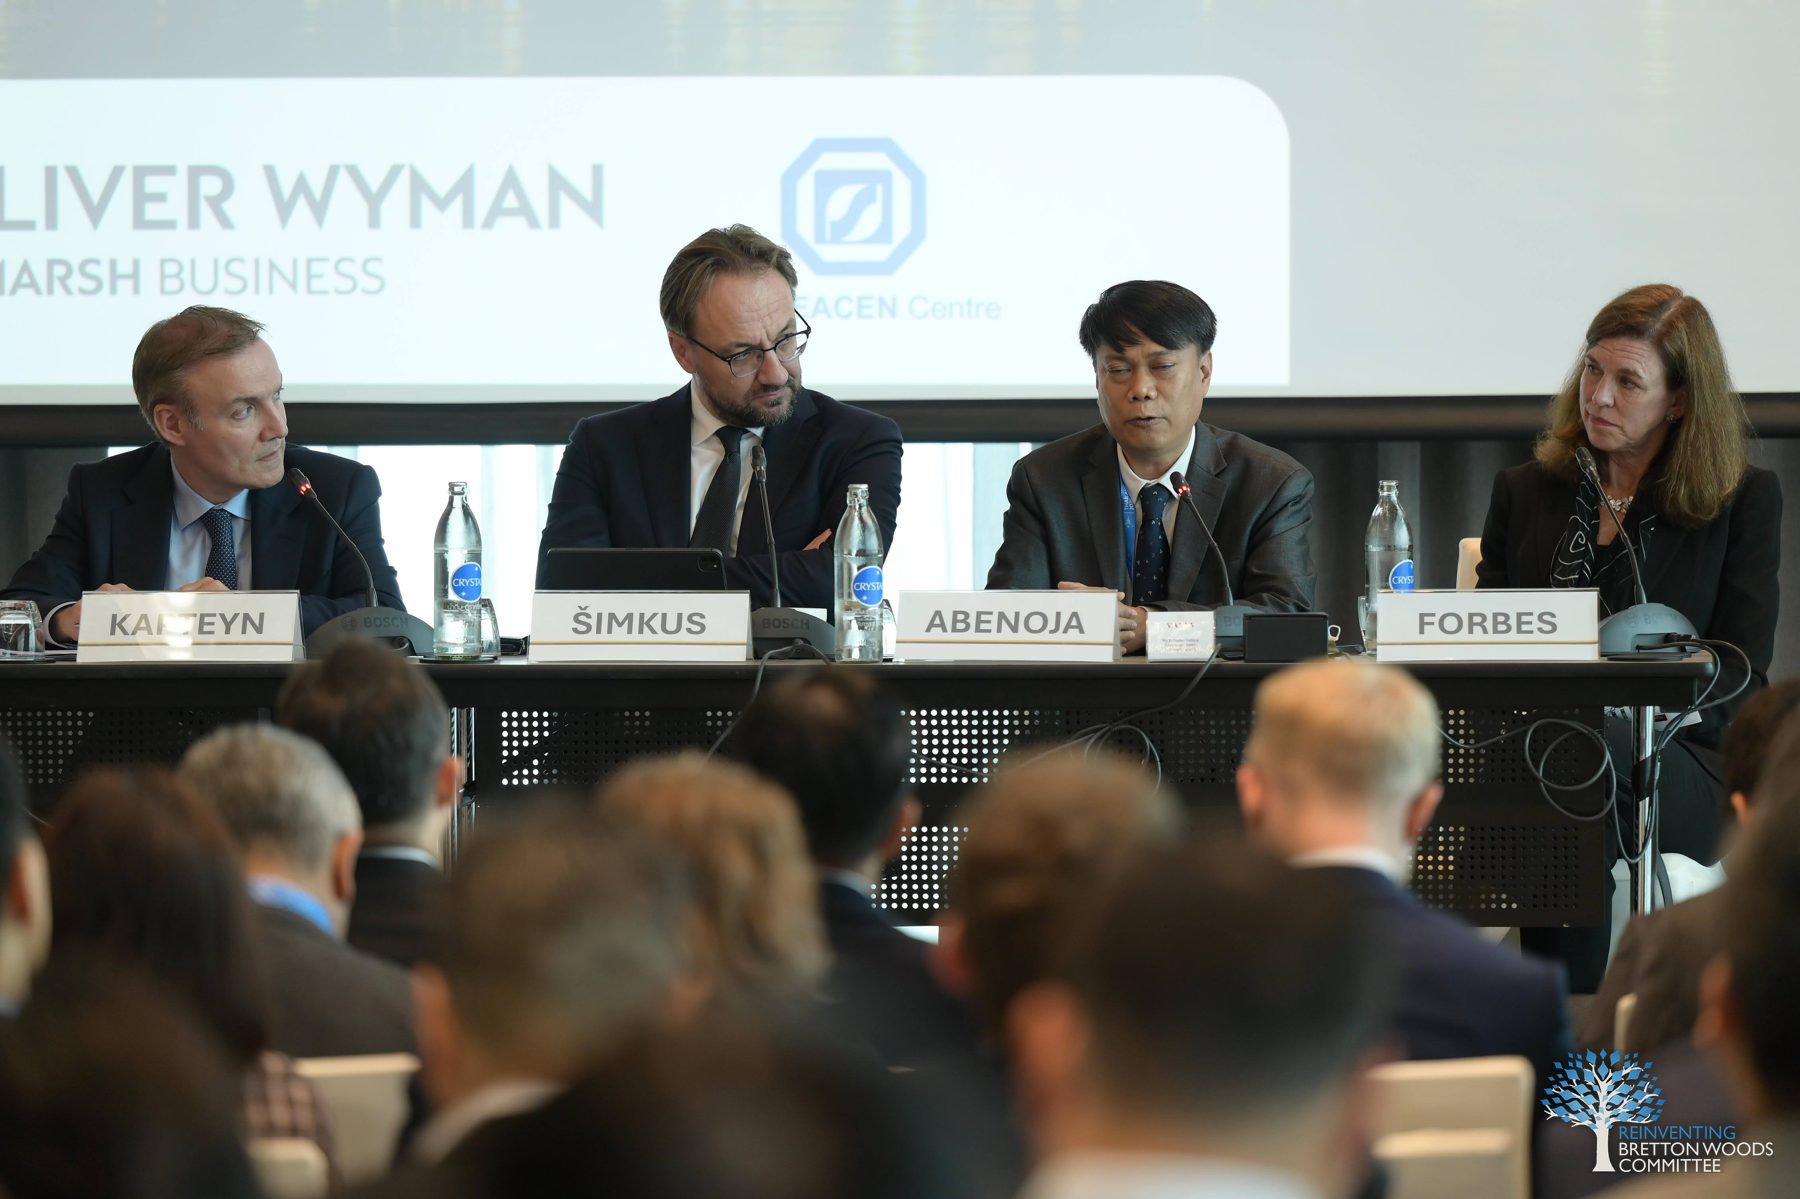
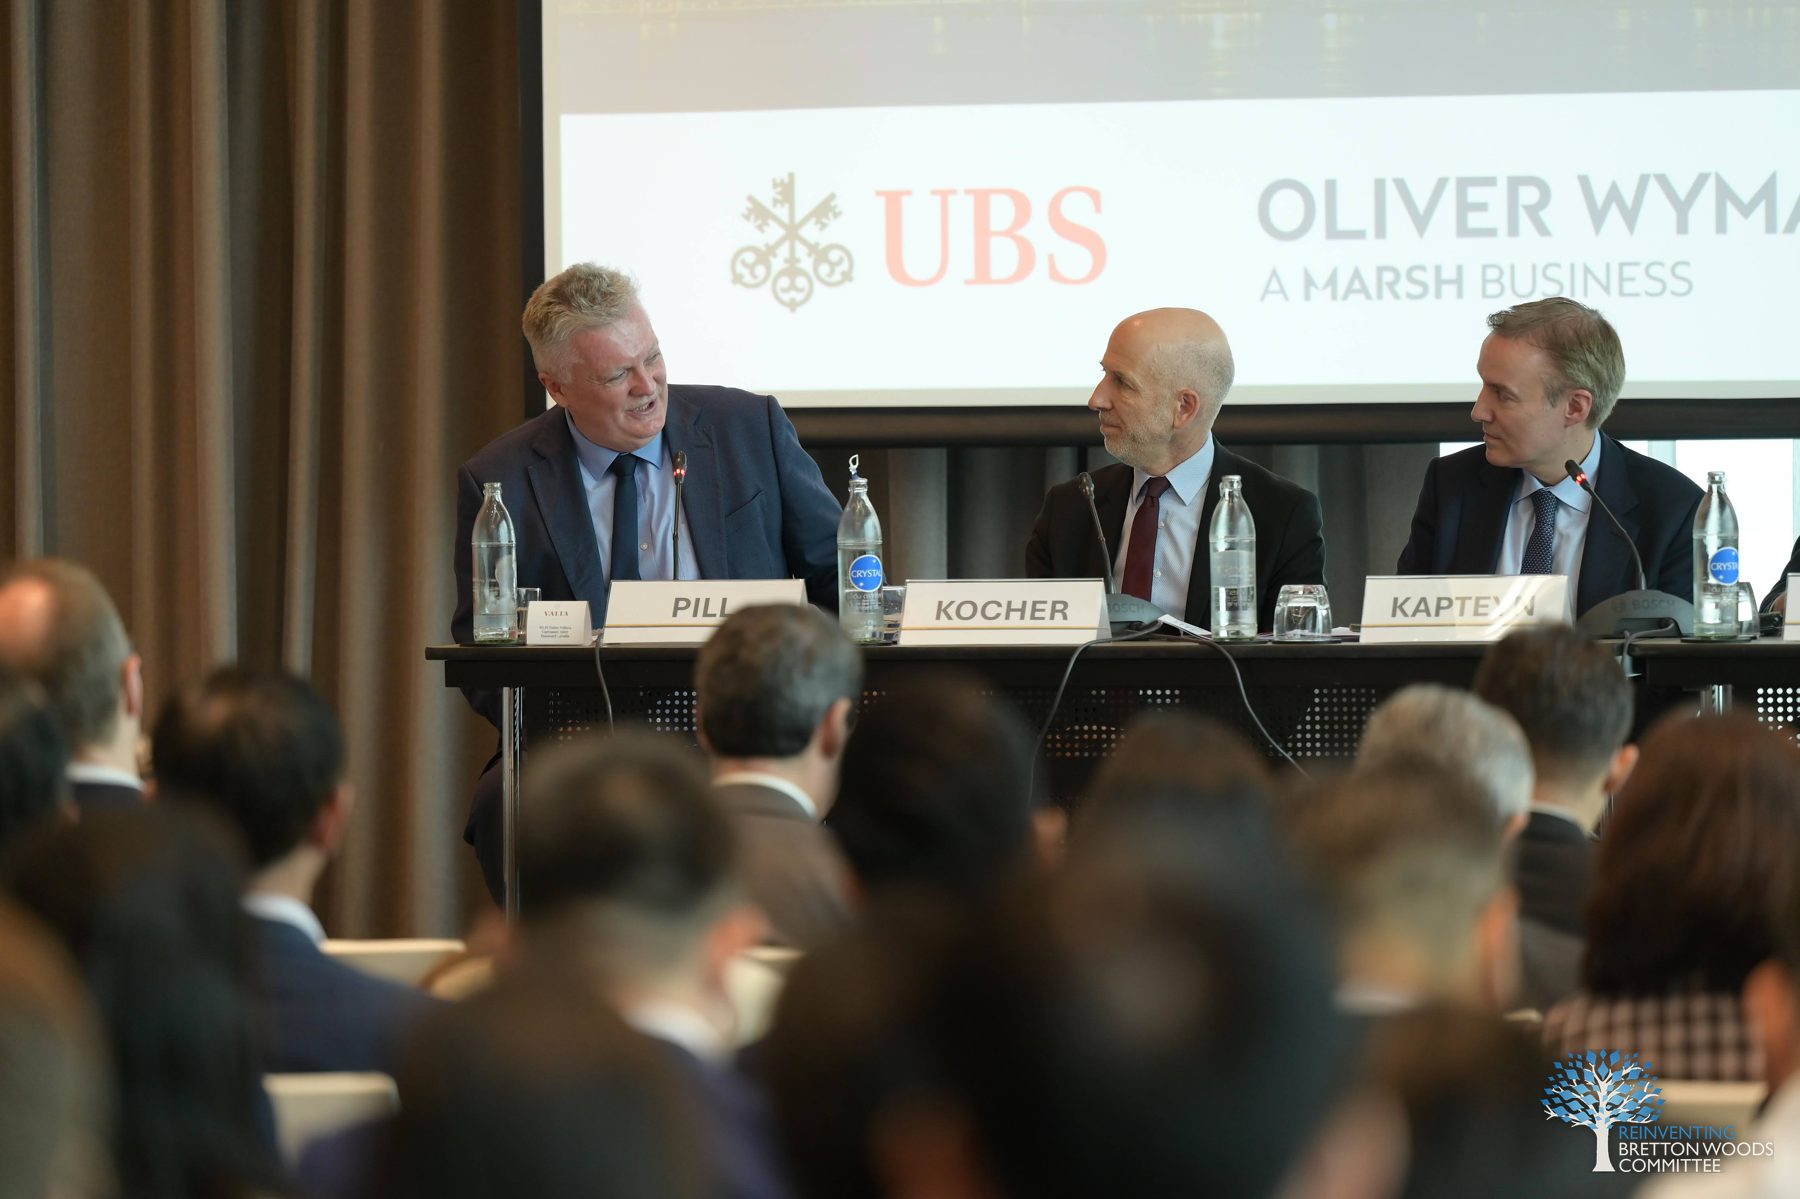
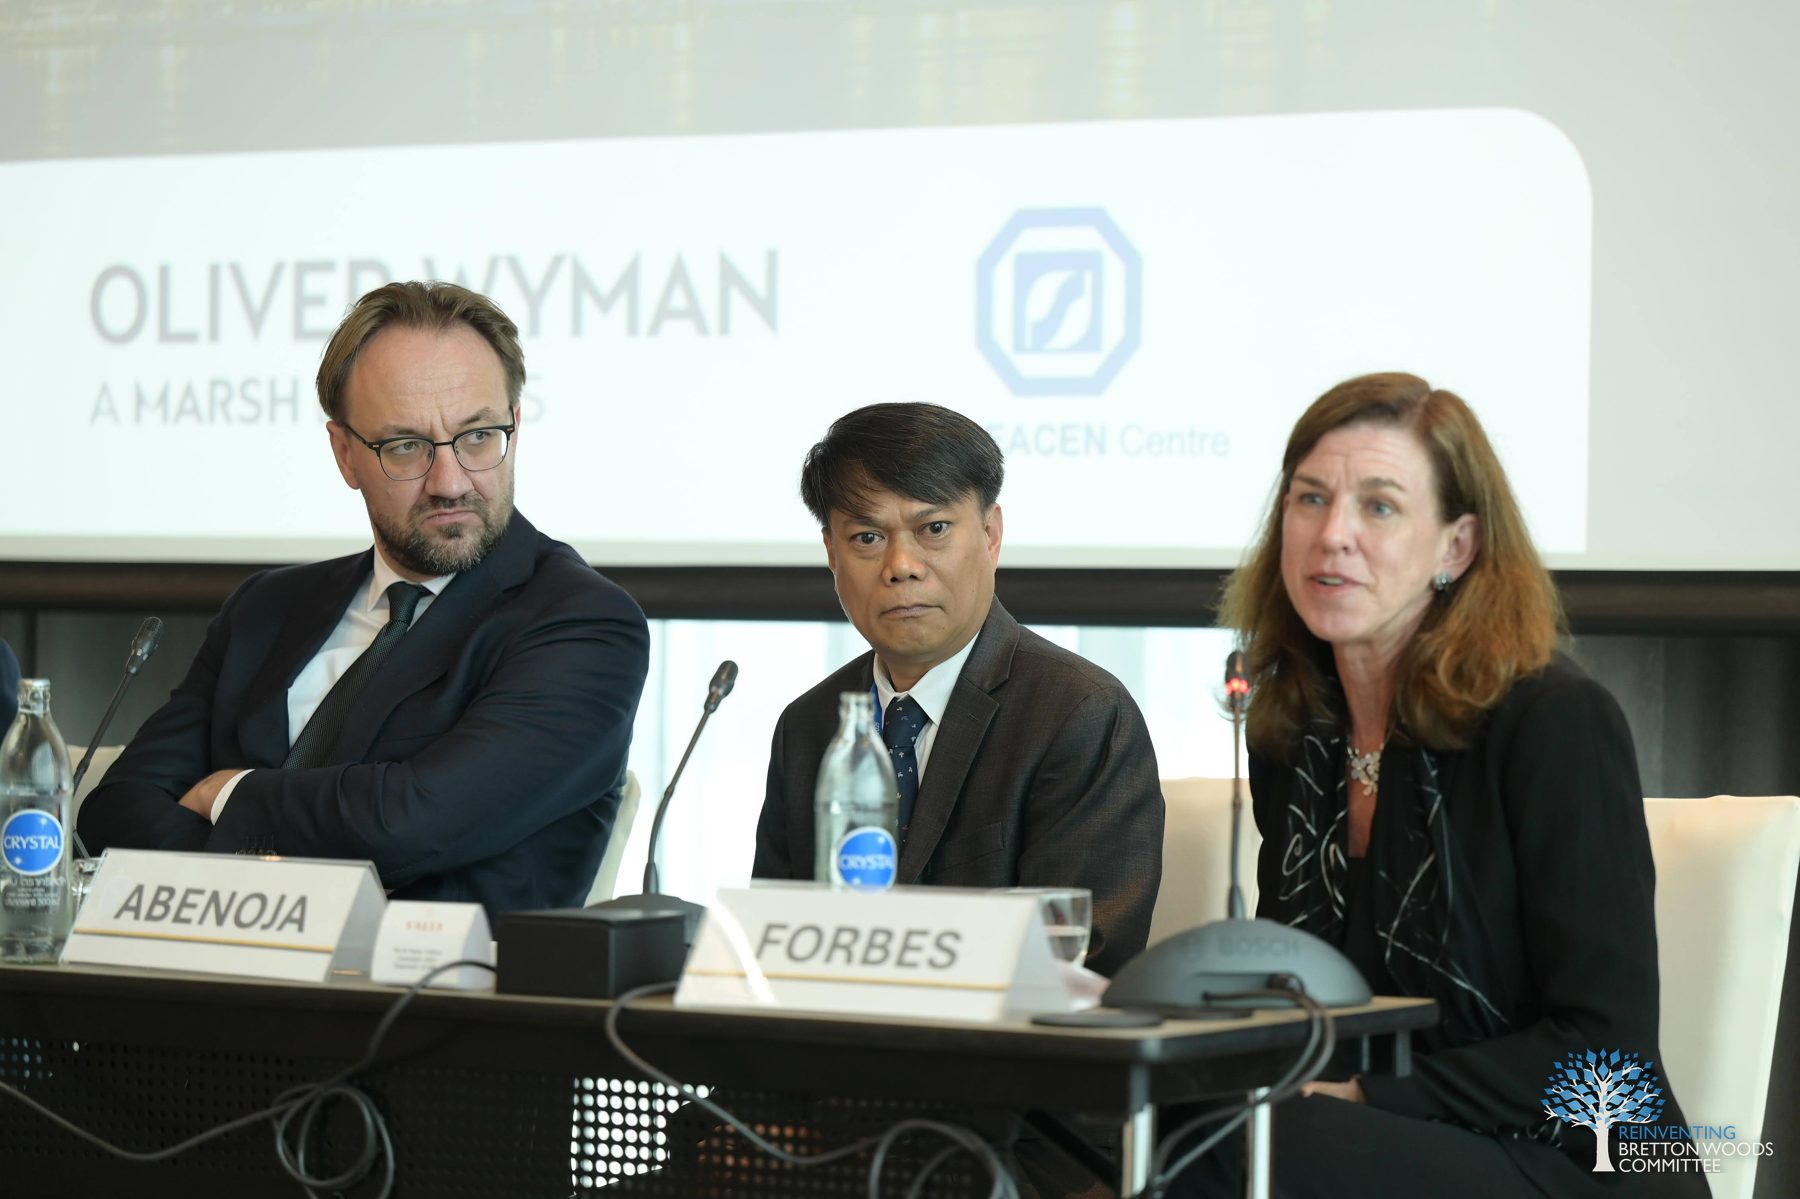
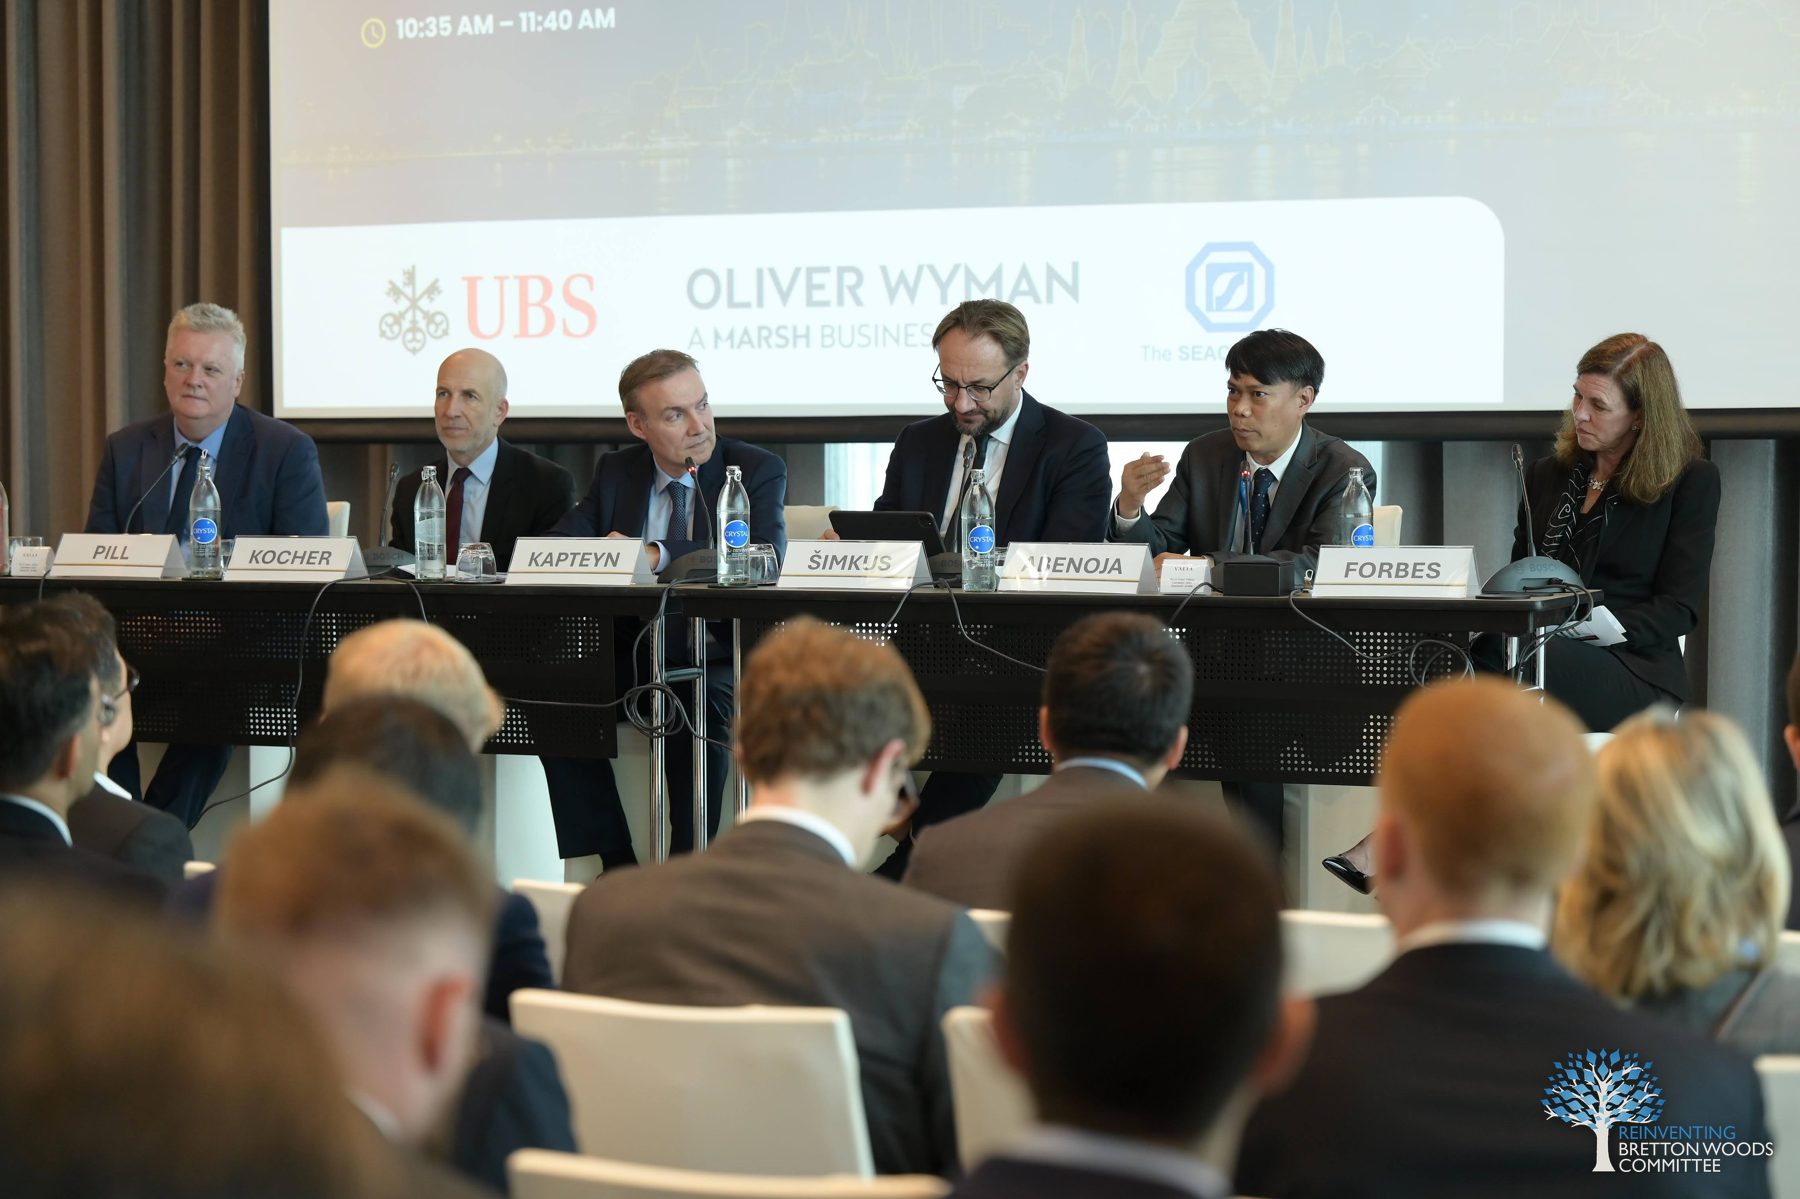
  8. Session 4 — Rethinking Monetary Policy for a Shock-Prone World

    Kristin Forbes Professor of Economics, MIT

    Martin Kocher Governor, Austrian National Bank

    Gediminas Šimkus Chairman of the Board, Bank of Lithuania and Member, ECB Governing Council

    Huw Pill Chief Economist and Member of the Monetary Policy Committee, Bank of England

    Zeno Ronald R. Abenoja Deputy Governor, BSP

    Arend Kapteyn Global Chief Economist, UBS

    (Chair)

  9. Section II: Money & monetary sovereignty
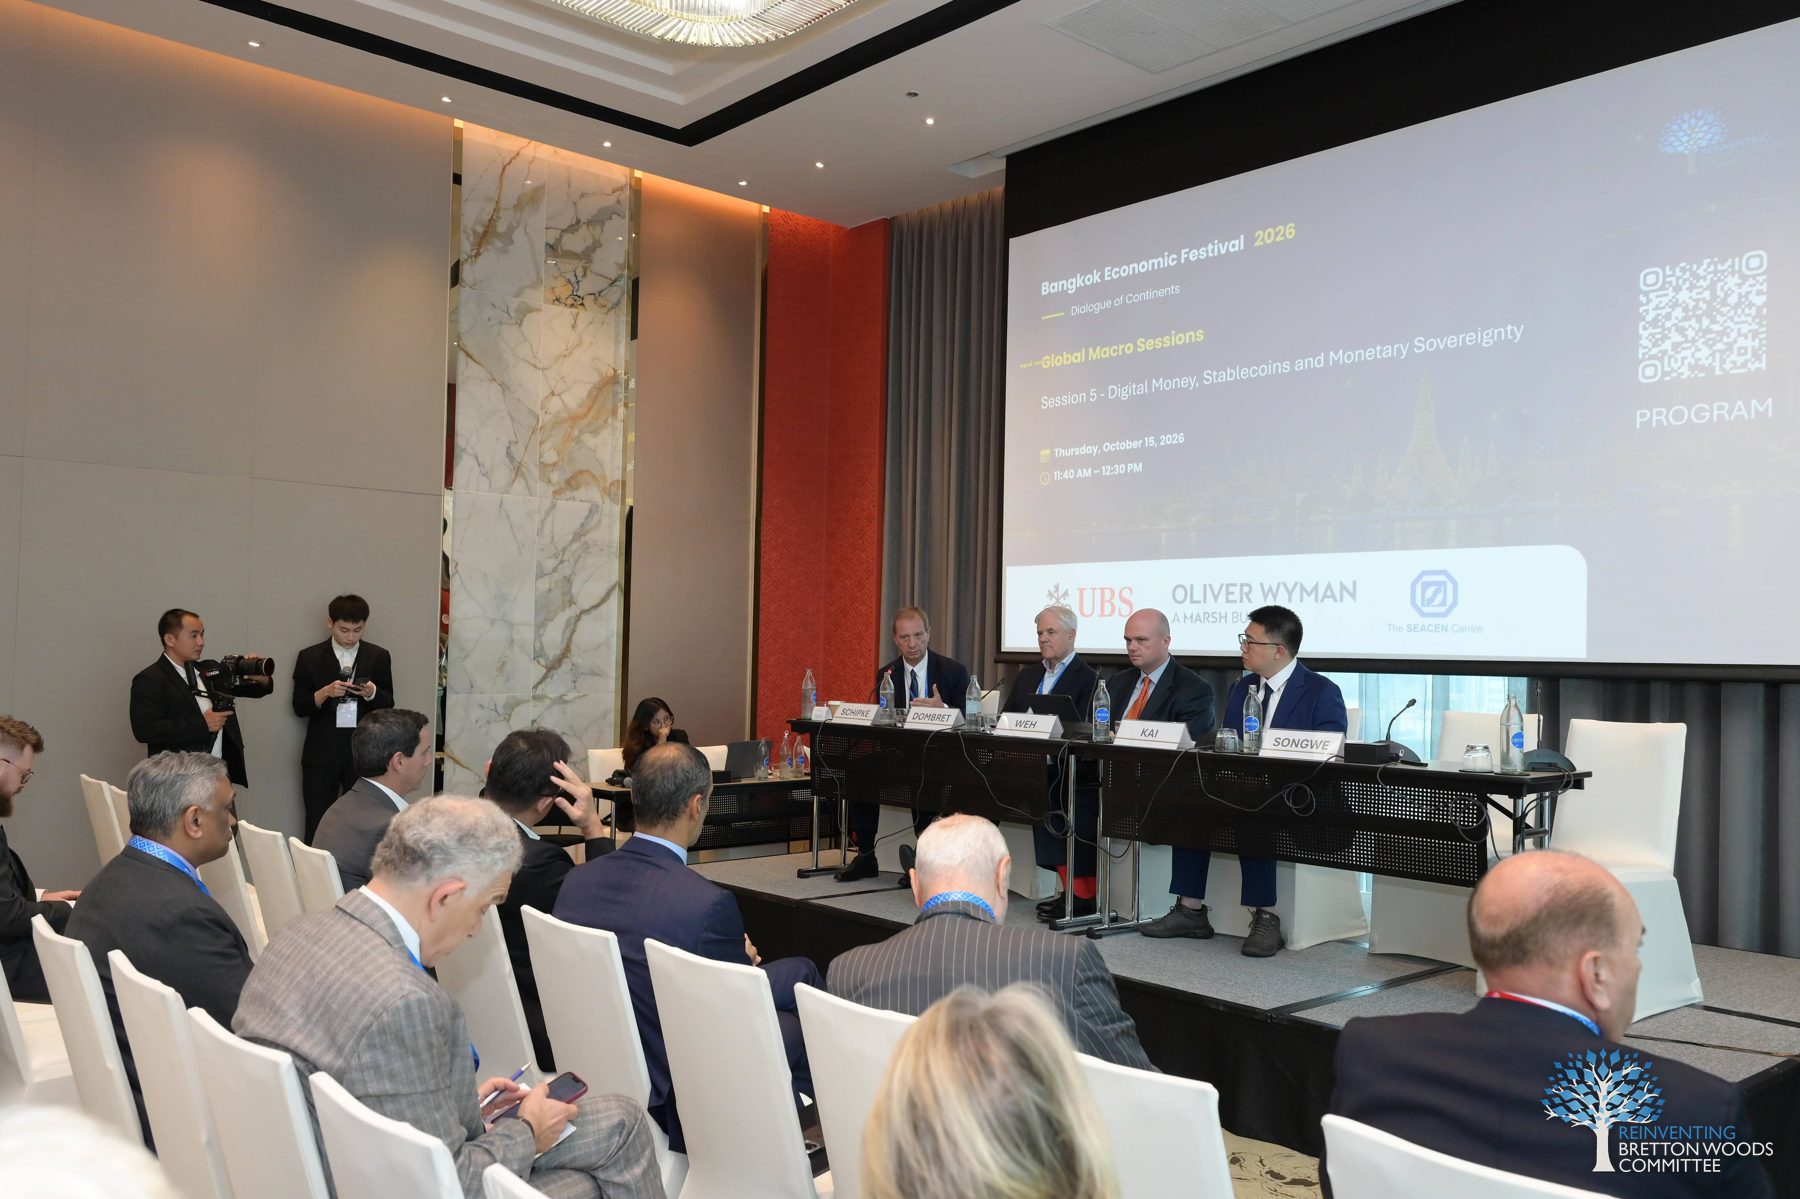
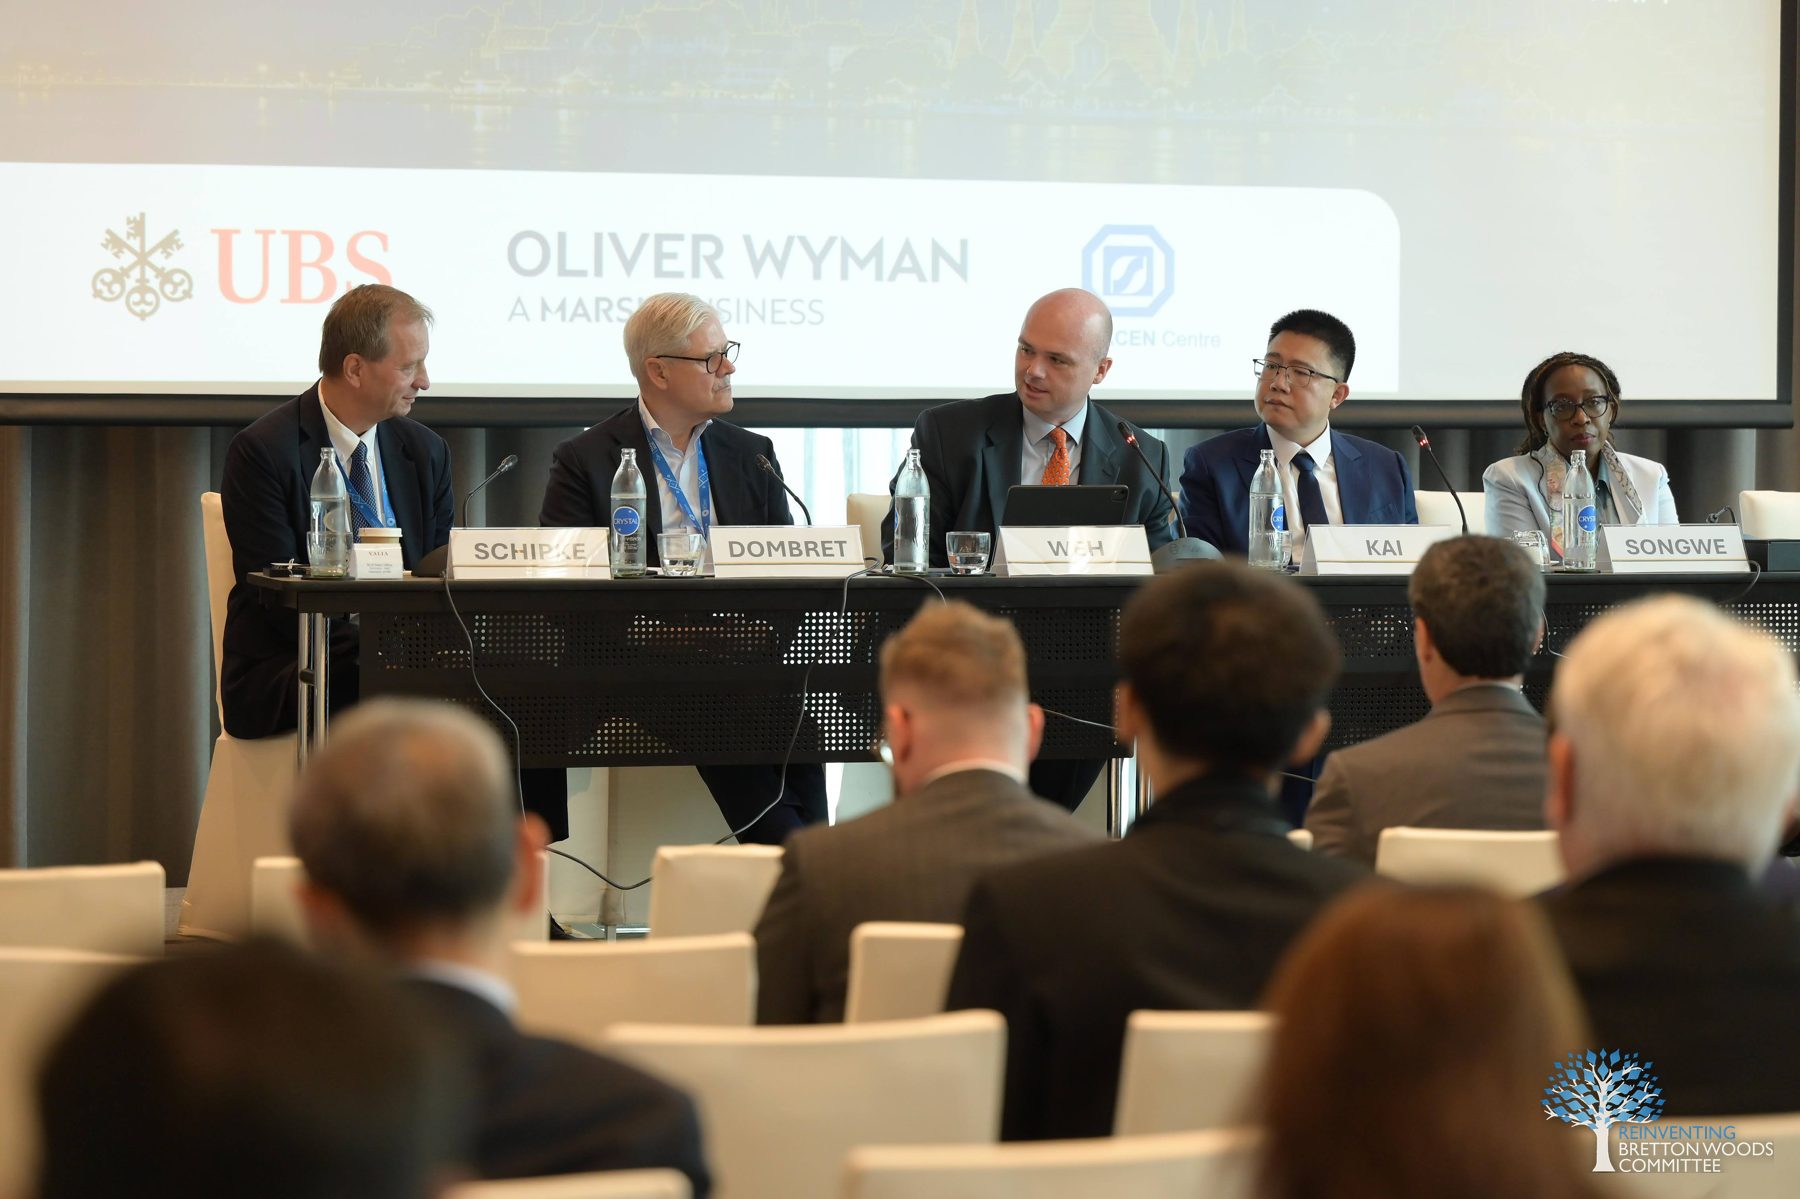
  10. Session 5- Digital Money, Stablecoins and Monetary Sovereignty

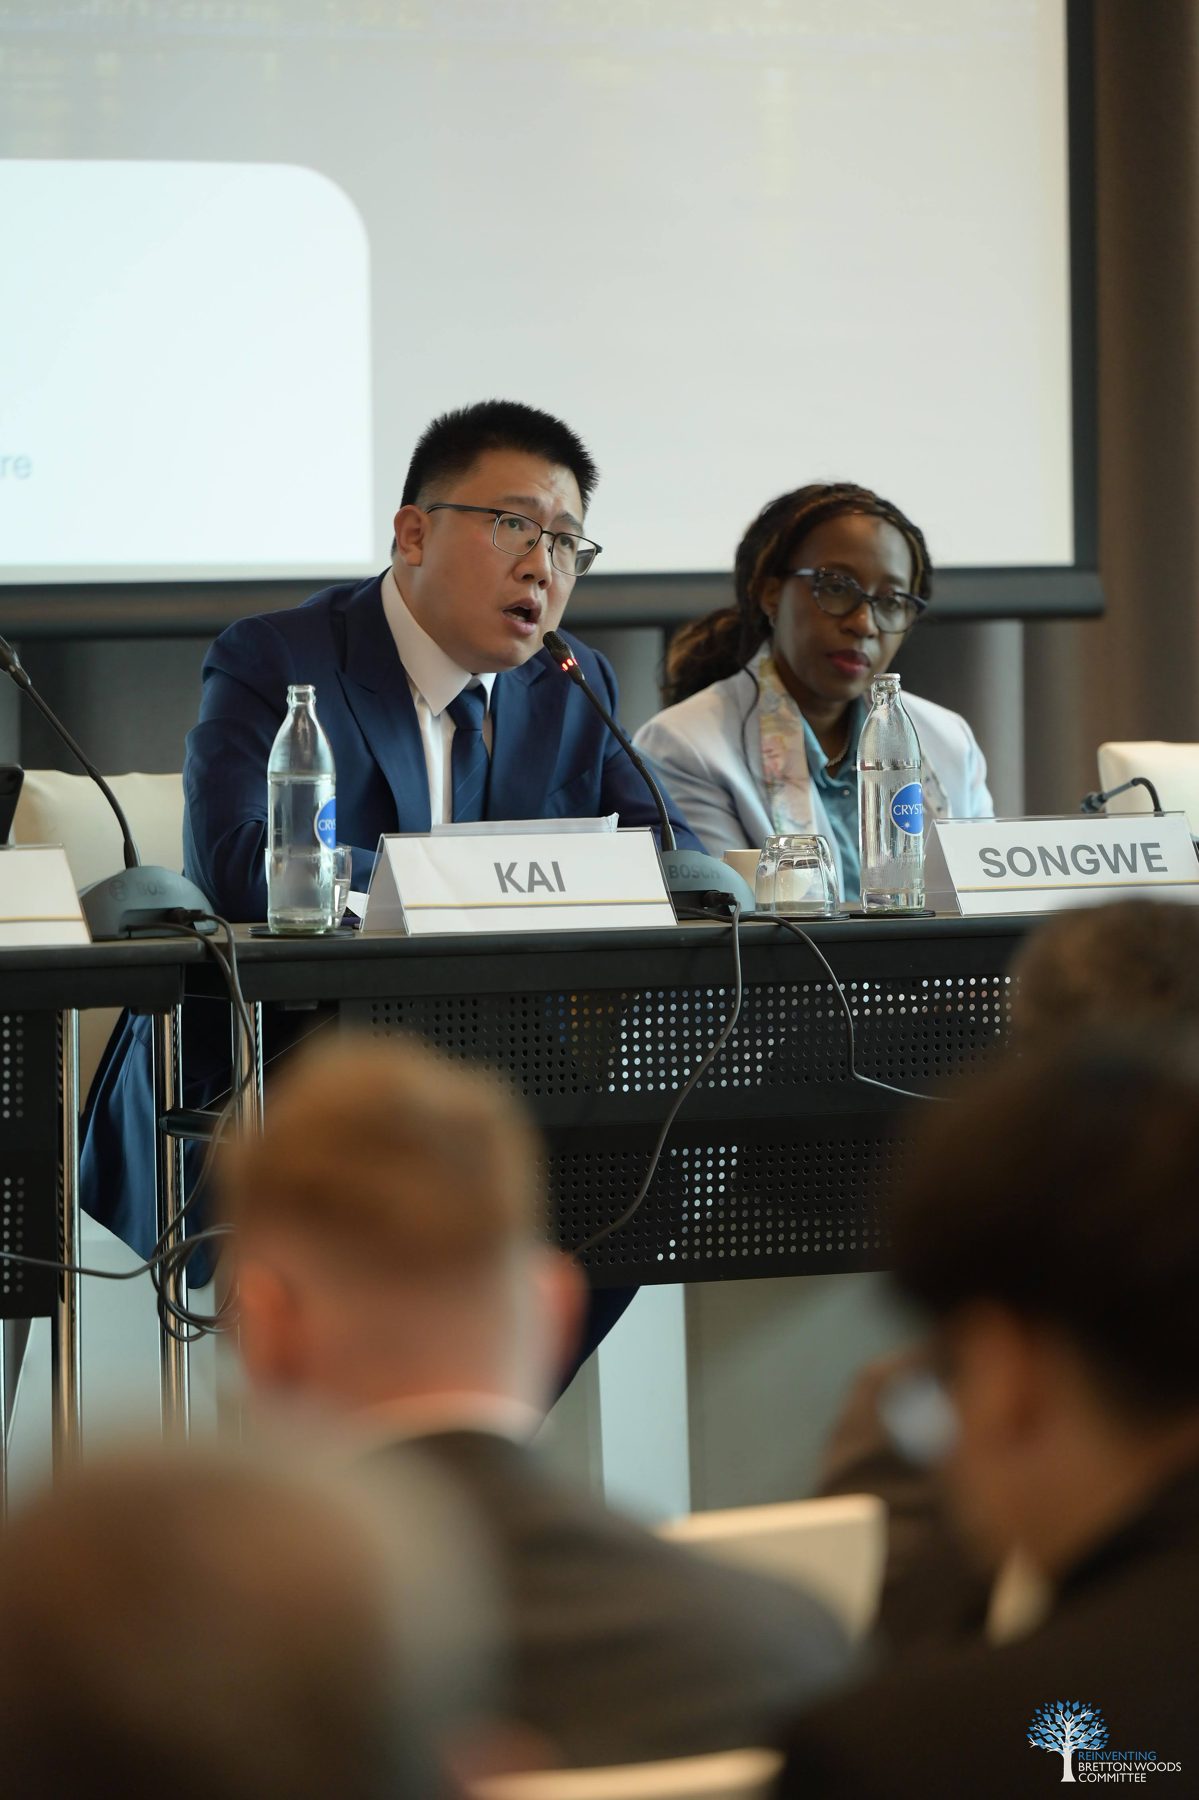
    Li Kai Chair Professor of Finance, PBC School of Finance, Tsinghua University

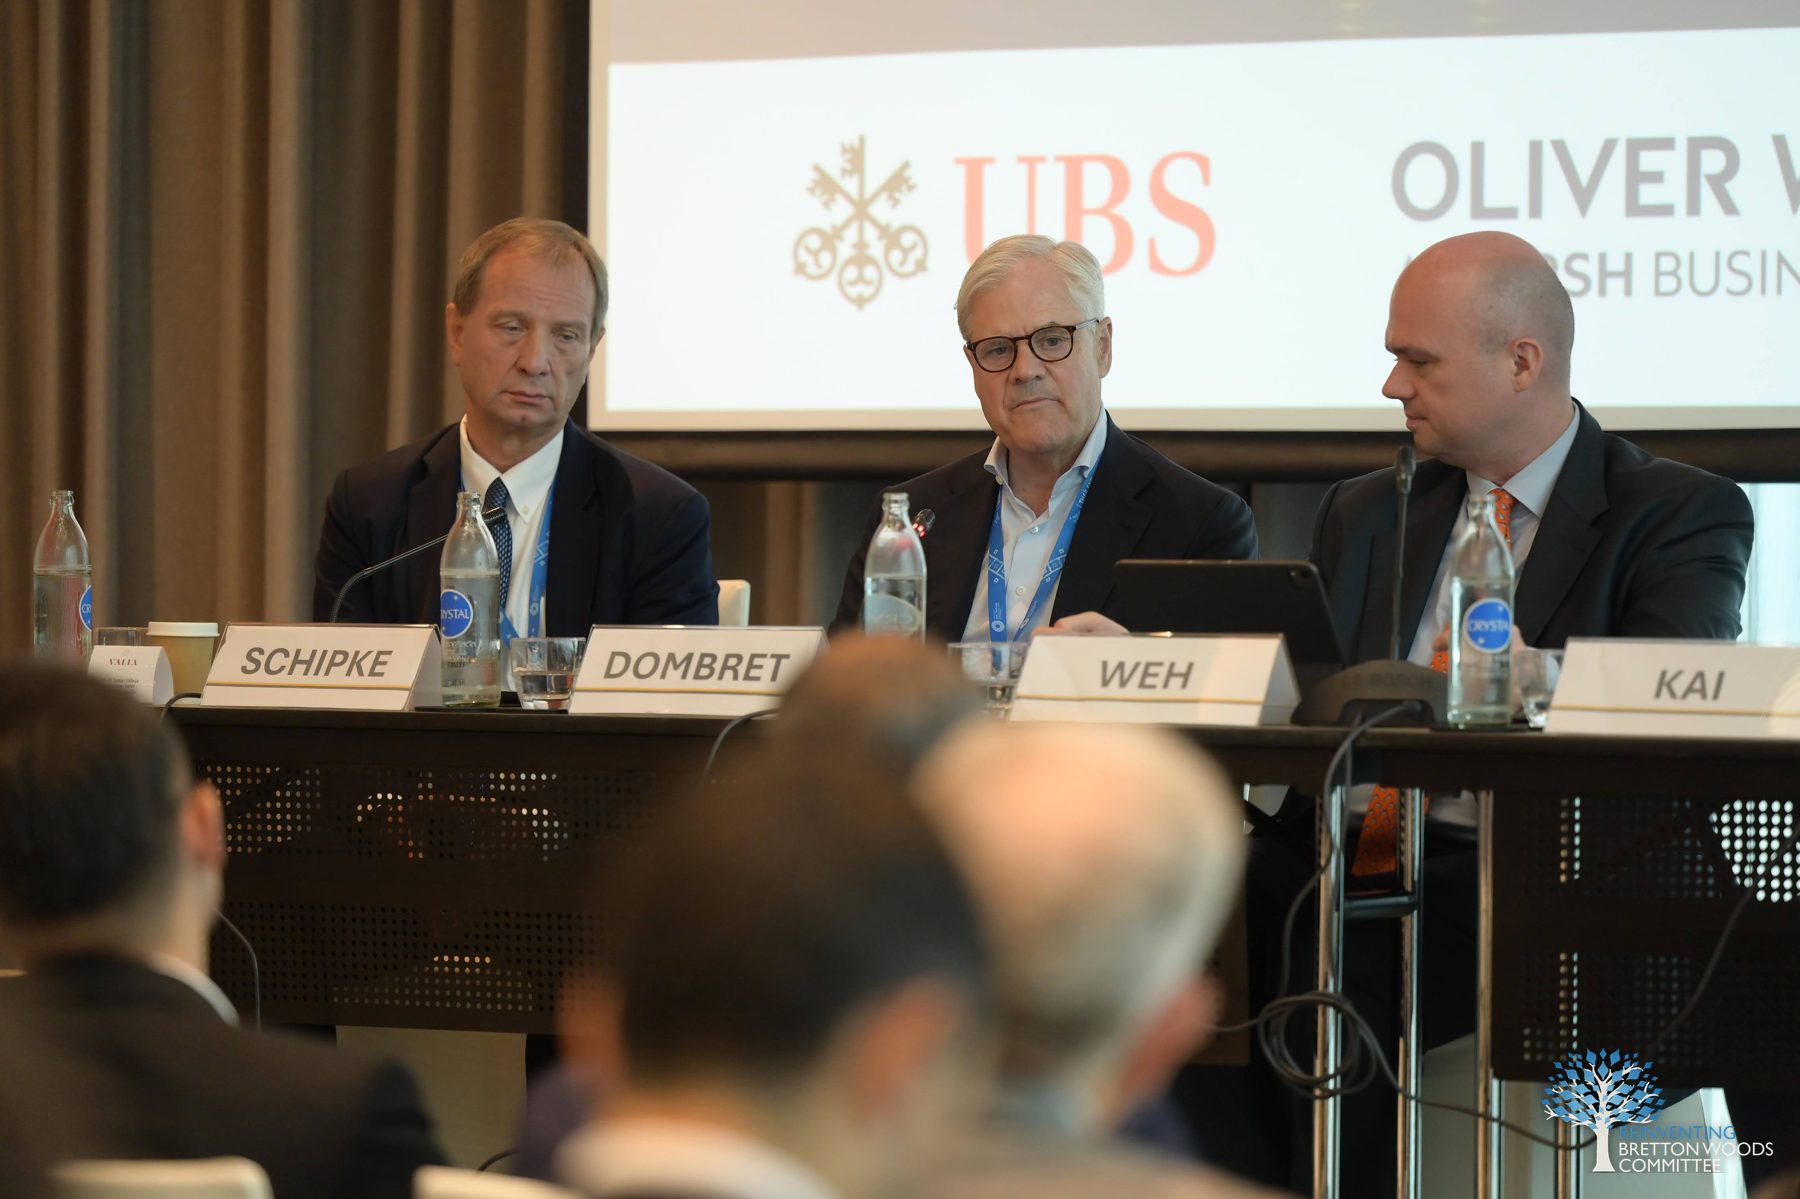
    Andreas Dombret Chairman of the Board, N26

    Alfred Schipke Director, East Asian Institute and Professor in practice Lee Kuan Yew School of Public Policy, National University of Singapore

    Vera Songwe Chair and Founder, Liquidity and Sustainability Facility

    Dominik Weh Partner, Oliver Wyman

    (Chair)

  11. Lunch

  12. Section III: Emerging markets
  13. Session 6 — Emerging Asia and LatAm: Preserving autonomy and resilience amid global

    fragmentation

    Daniel Palotai Deputy Governor of the Magyar

    Nemzeti

    Bank

    Guillermo Tolosa Governor Central Bank of Uruguay

    Nouriel Roubini Emeritus Professor of Economics, NYU

    Rogelio Mercado Assistant Governor, Central Bank of the Philippines

    Massimiliano Castelli Head, Global Sovereign Markets Strategy and Advice, UBS Asset Management

    (Chair)

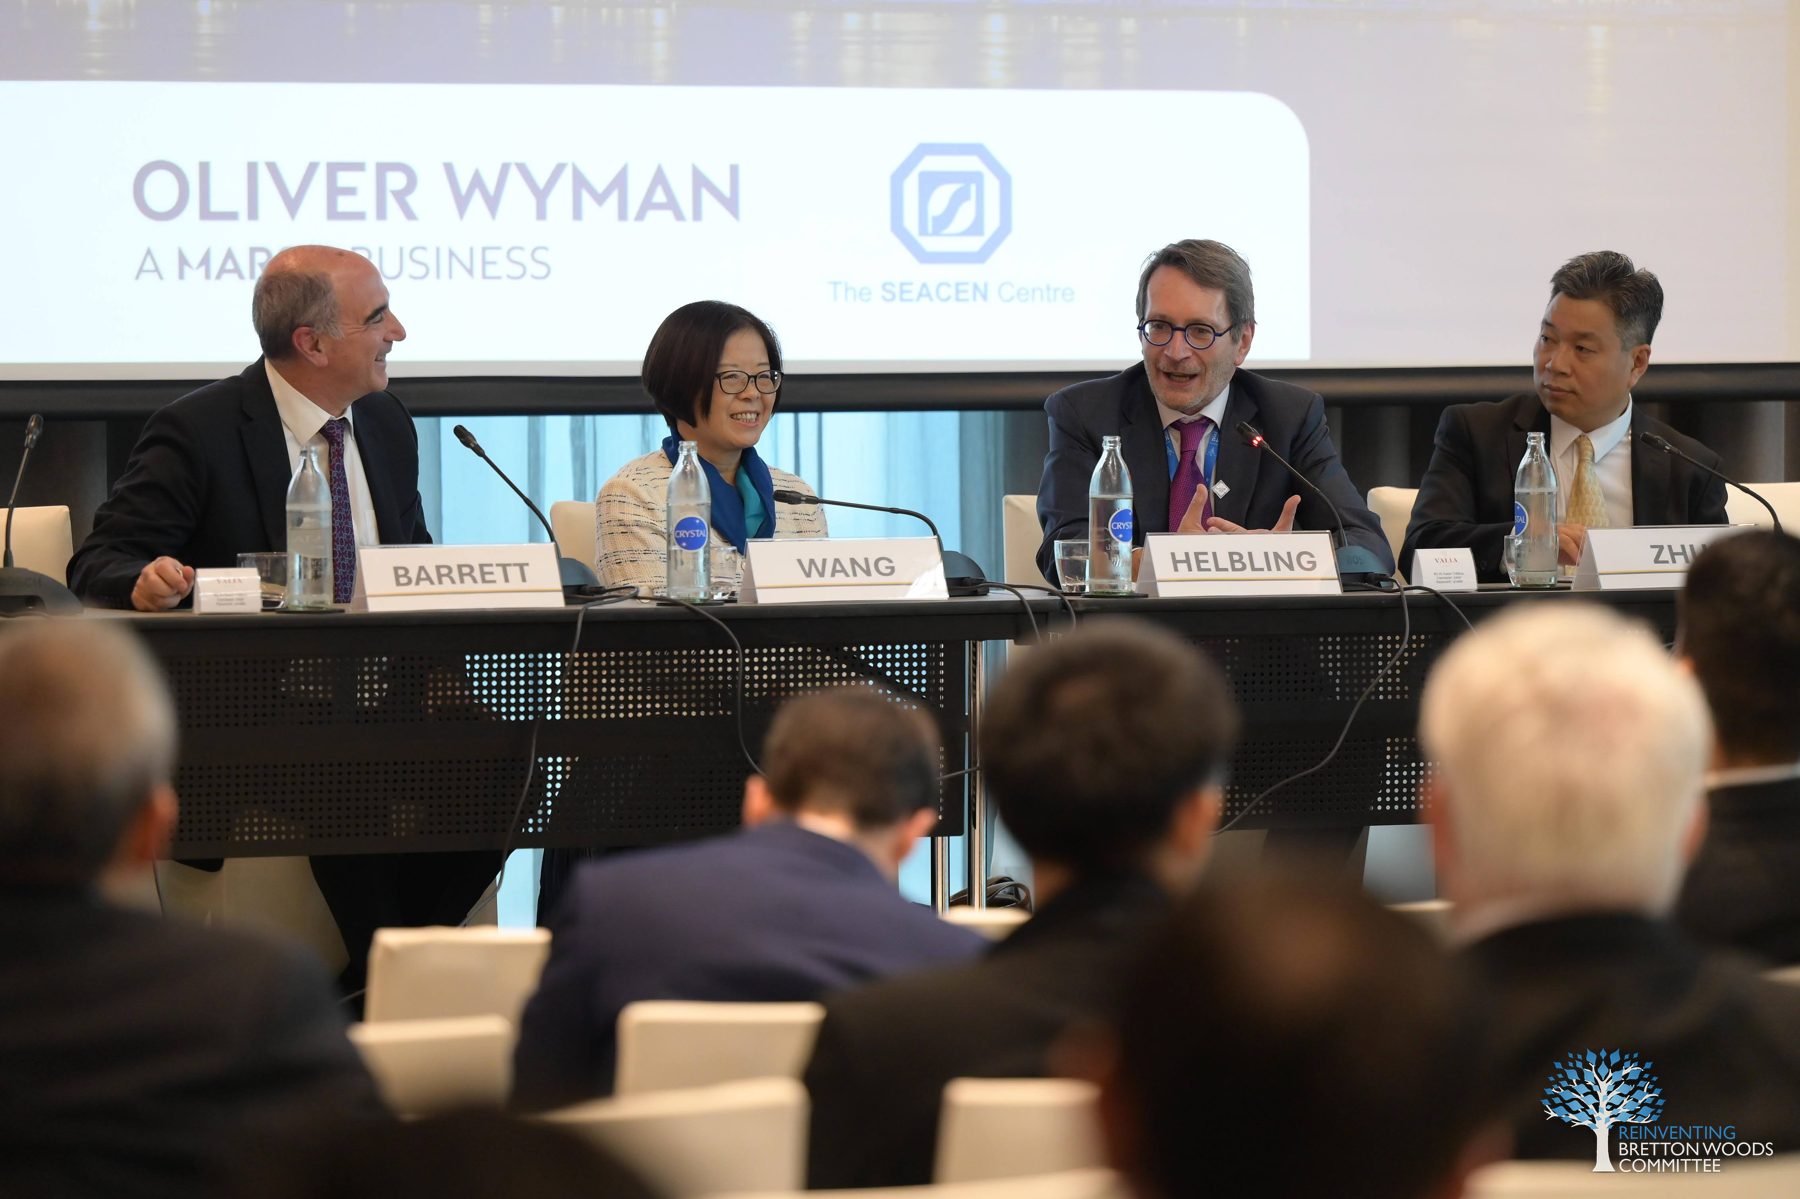
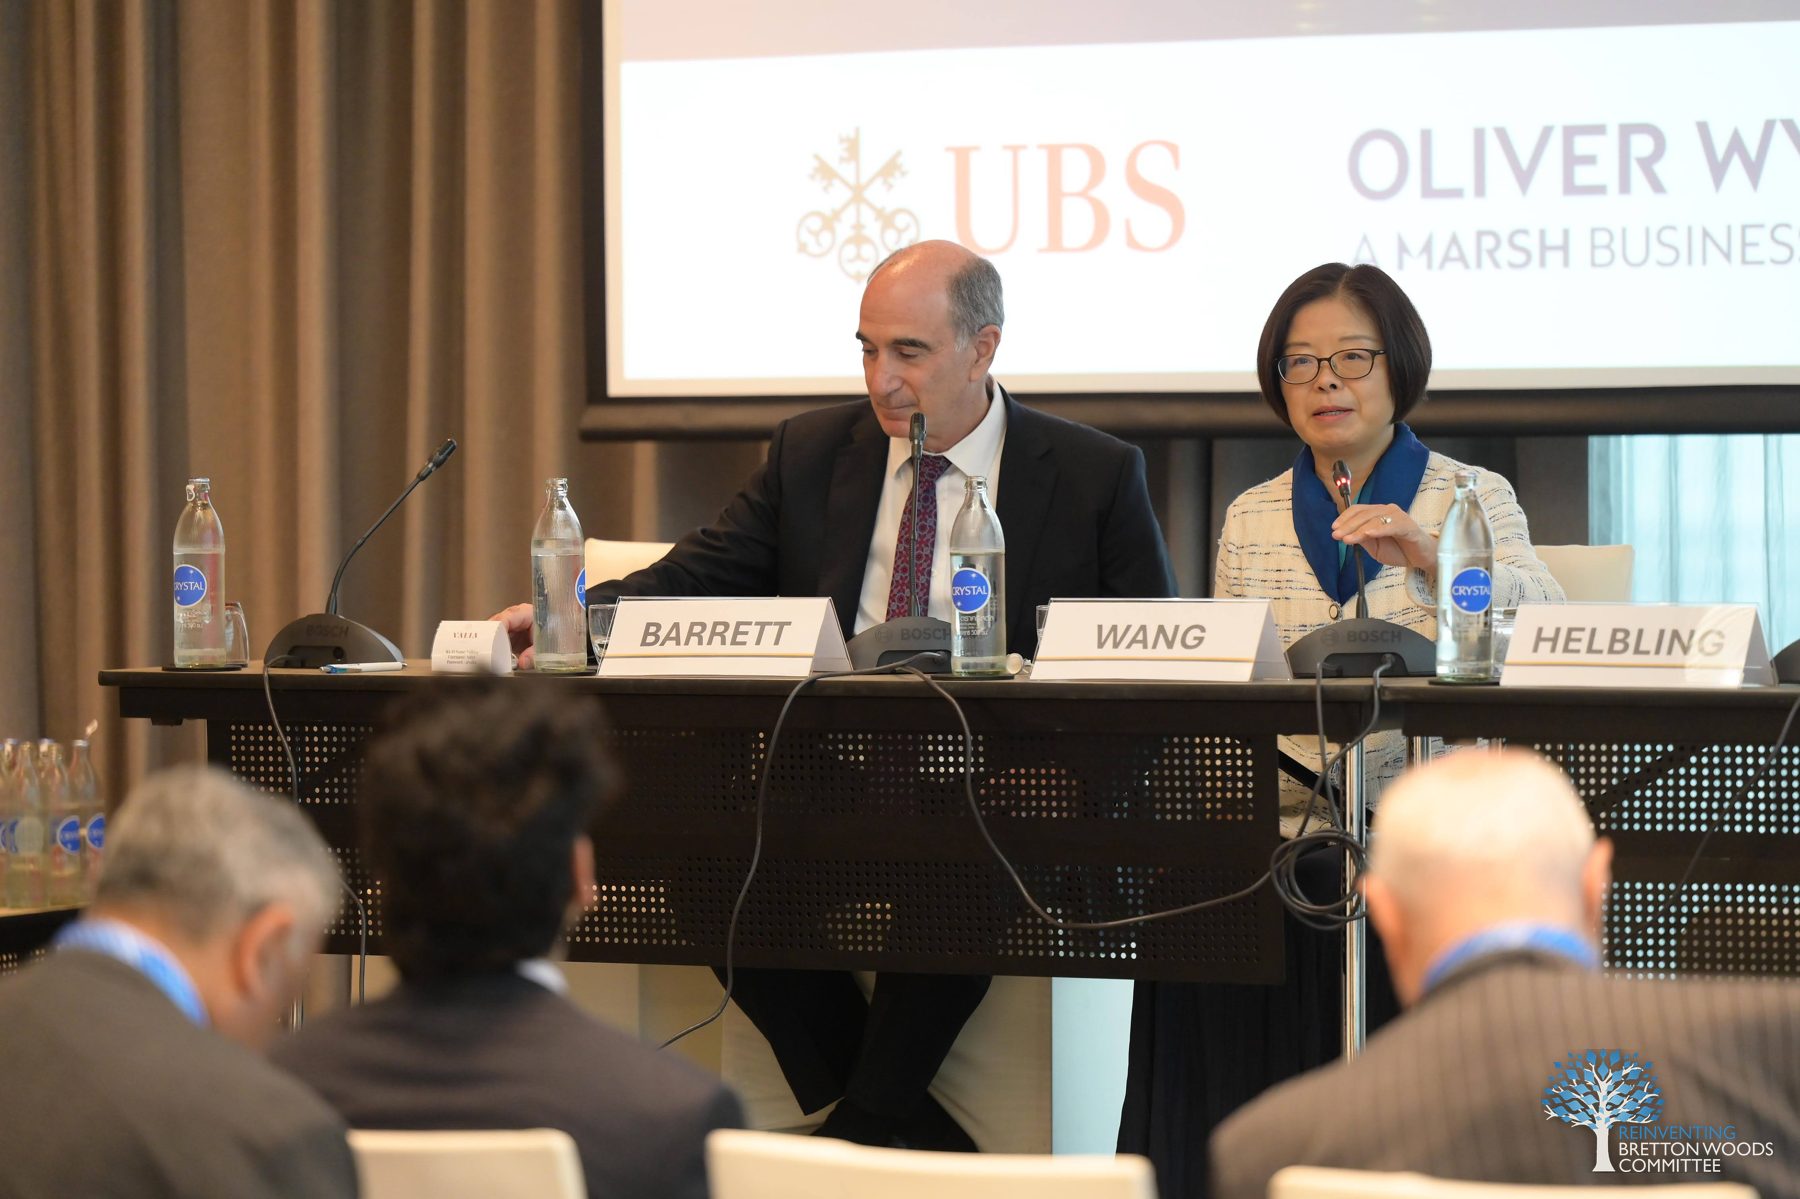
  14. Session 7 — China and the Global Economy: Is China Reflating?

    Haibin Zhu Executive Director, Hong Kong Monetary Authority

    Steven Barnett Professor of Economics, HKU

    Thomas Helbling Deputy Director, Asia and Pacific Department, IMF

    Tao Wang Senior Advisor, UBS

    (Chair)

  15. Coffee break

  16. Section IV: Closing debate
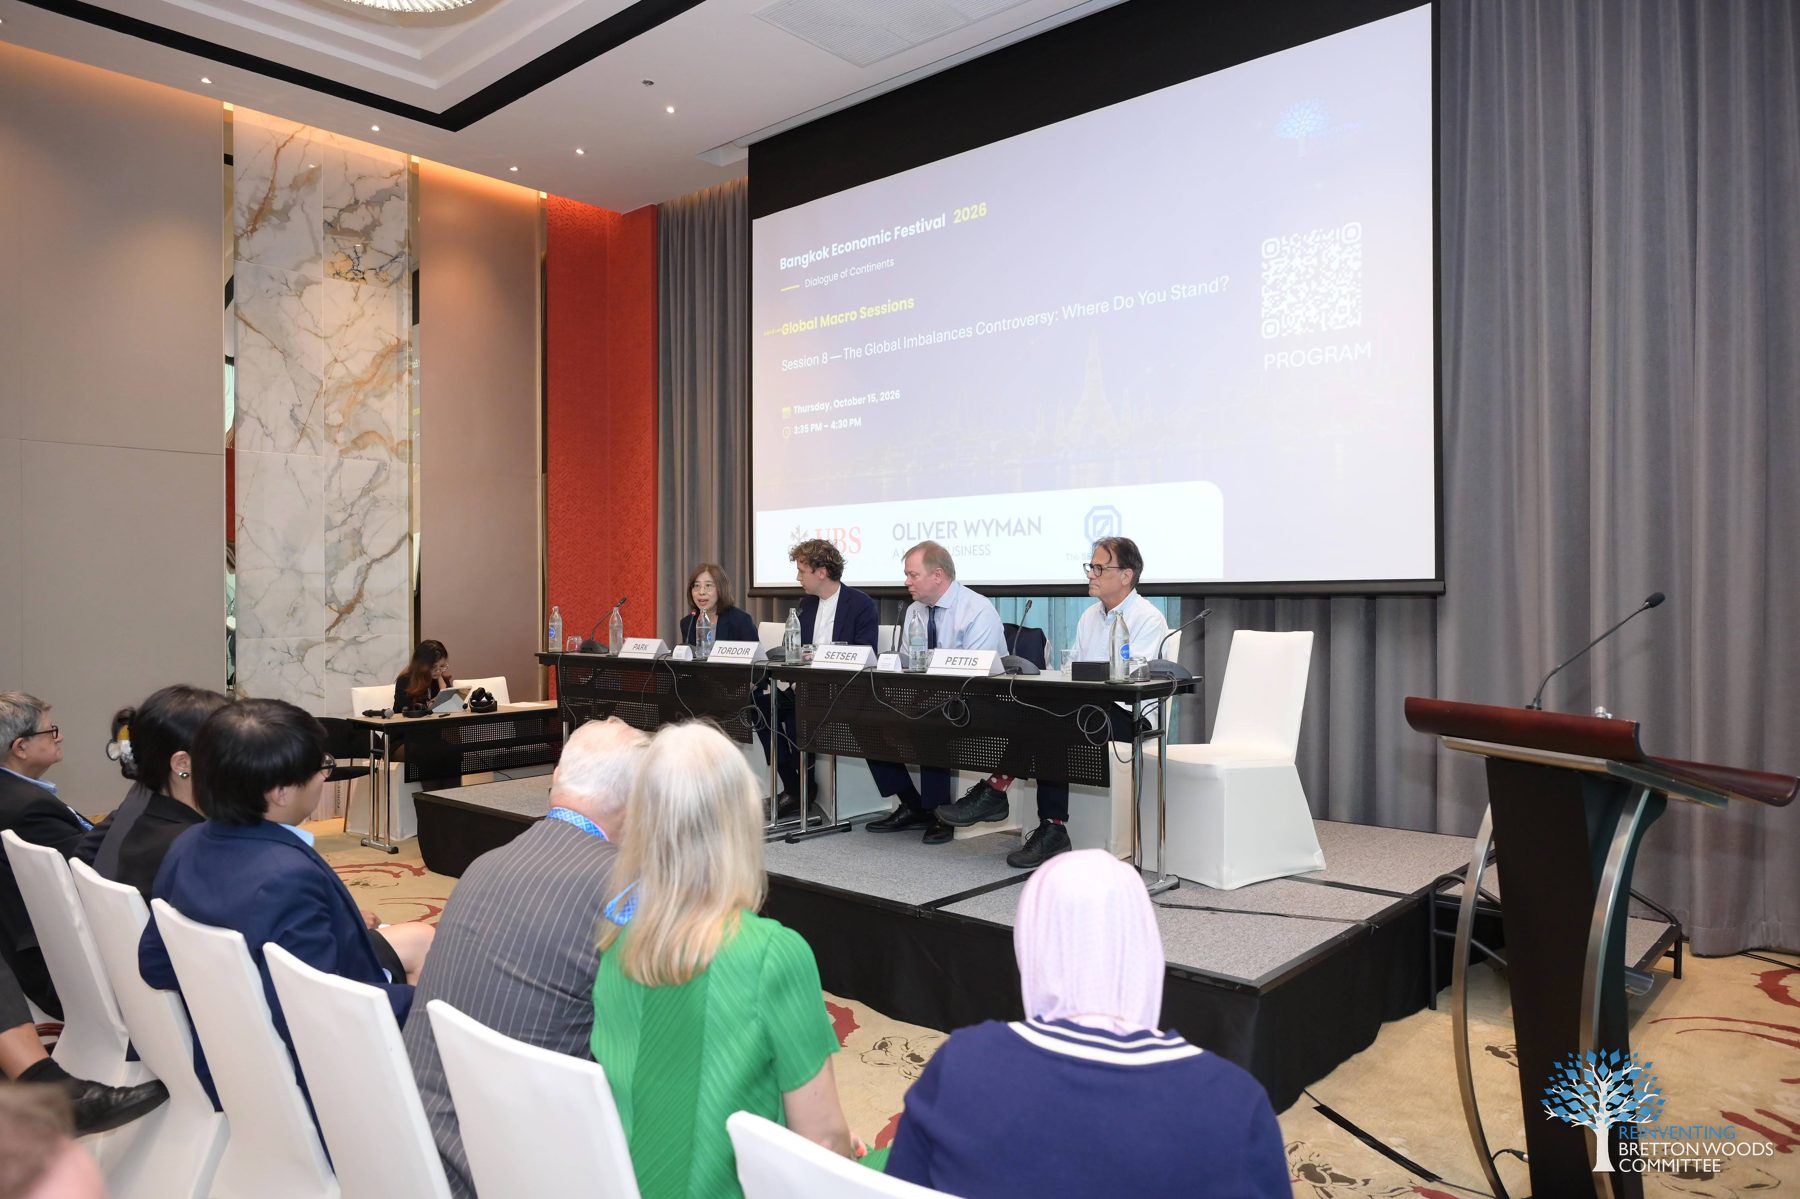
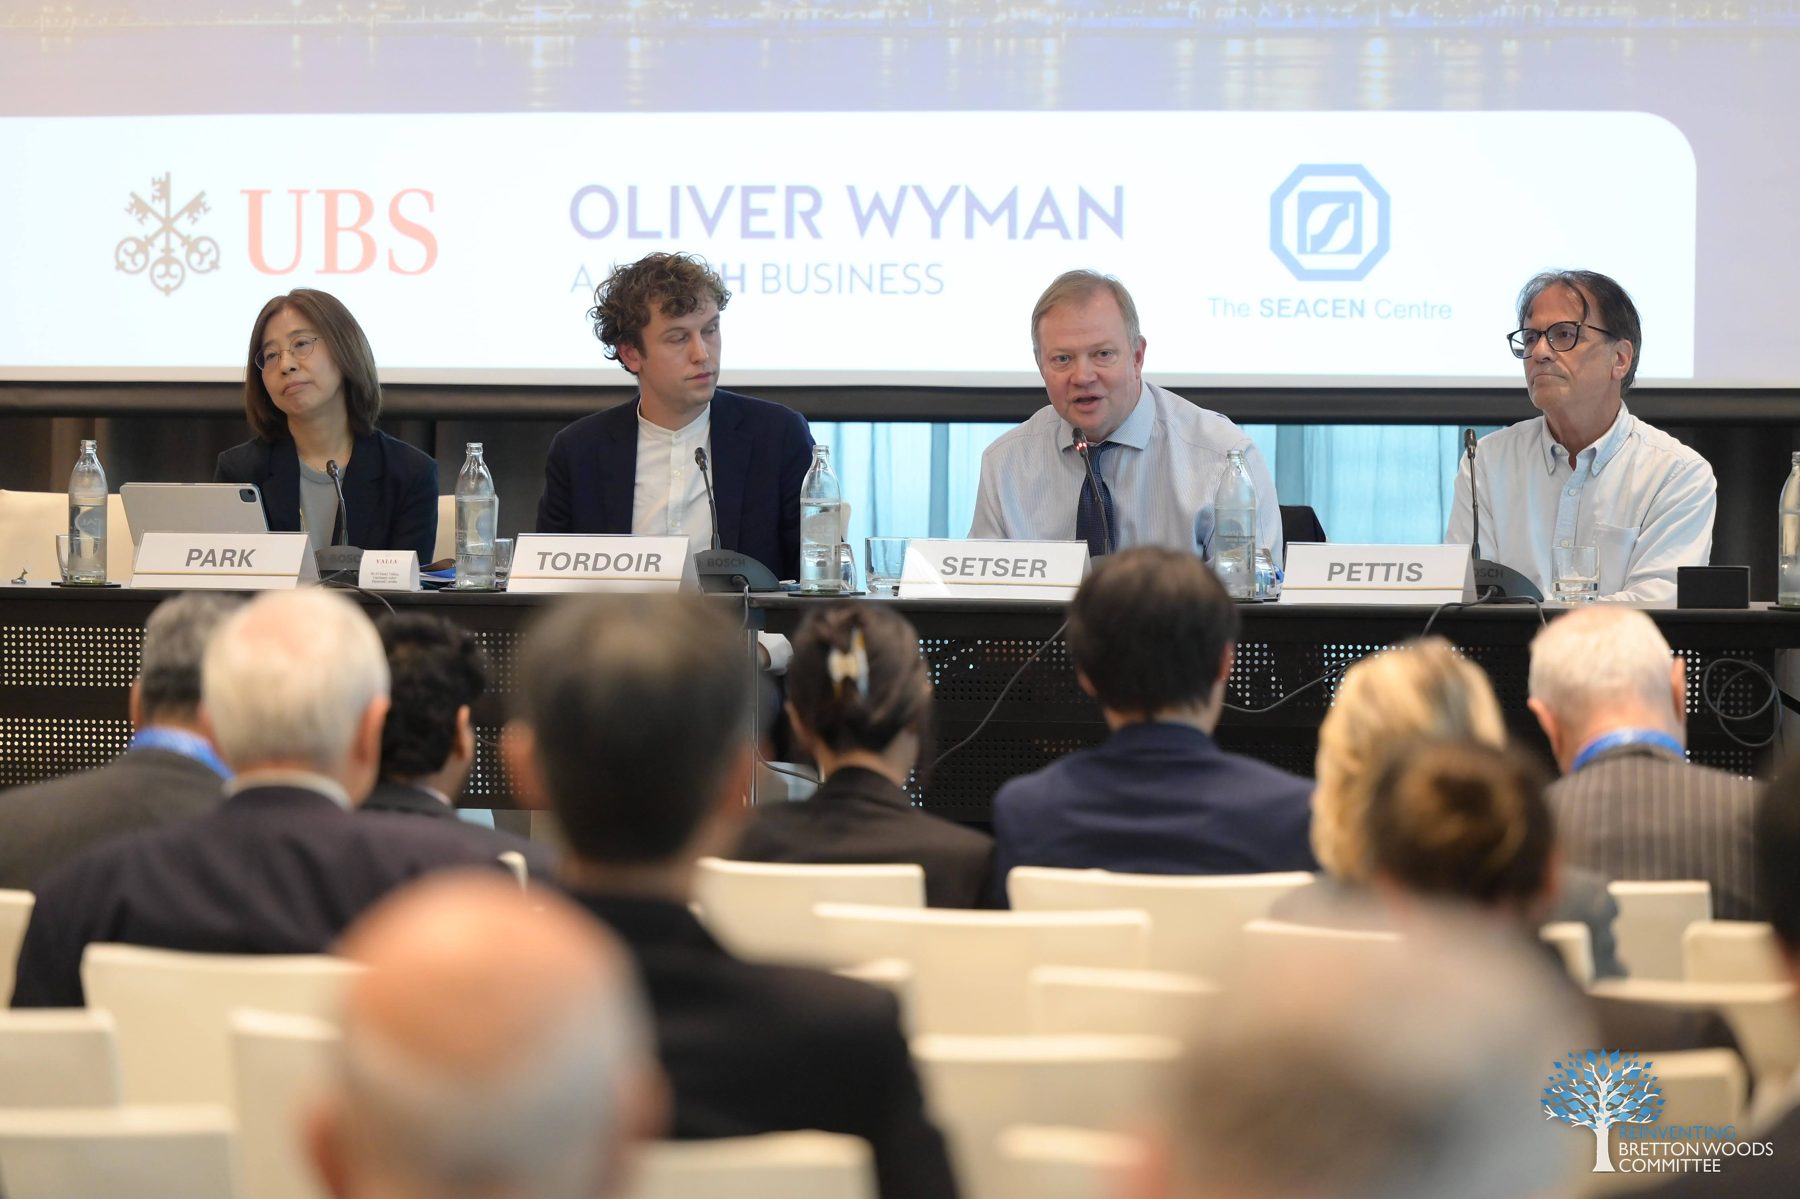
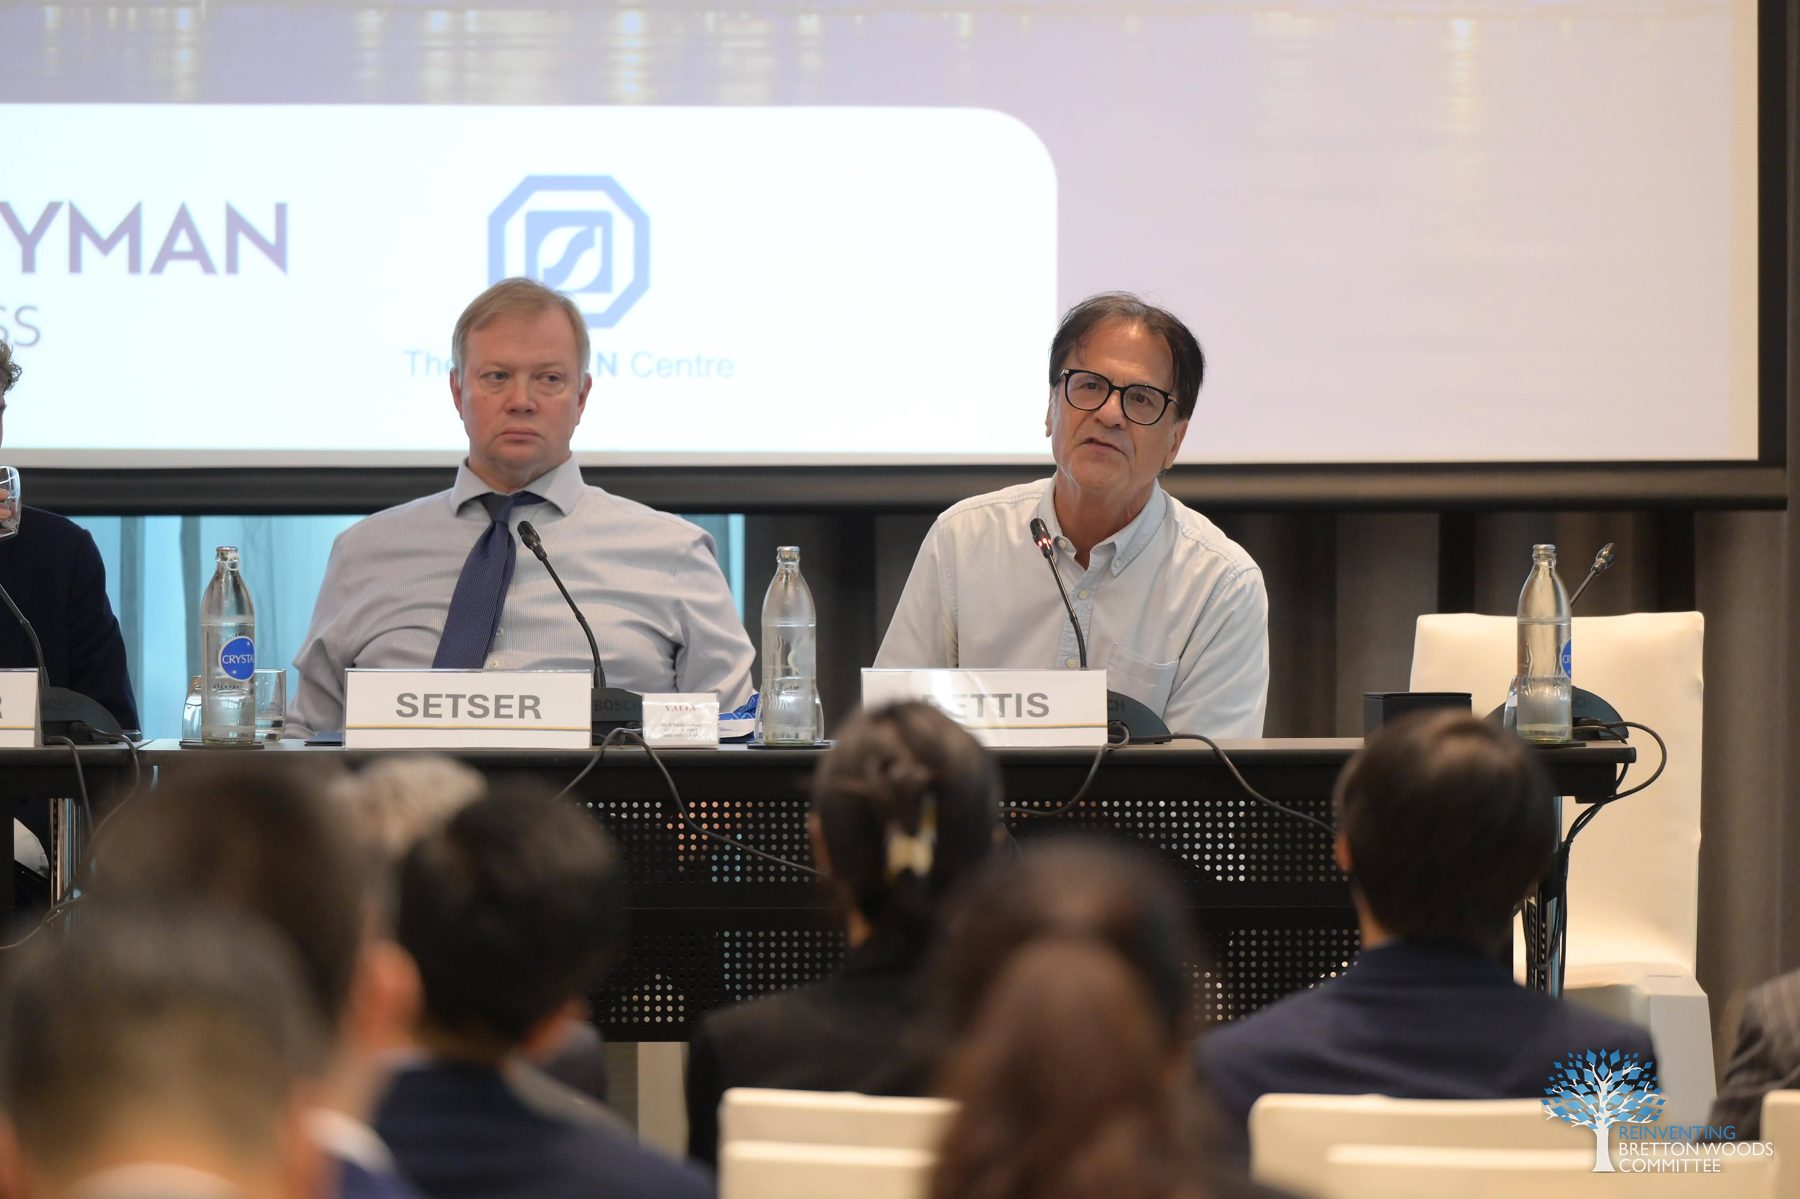
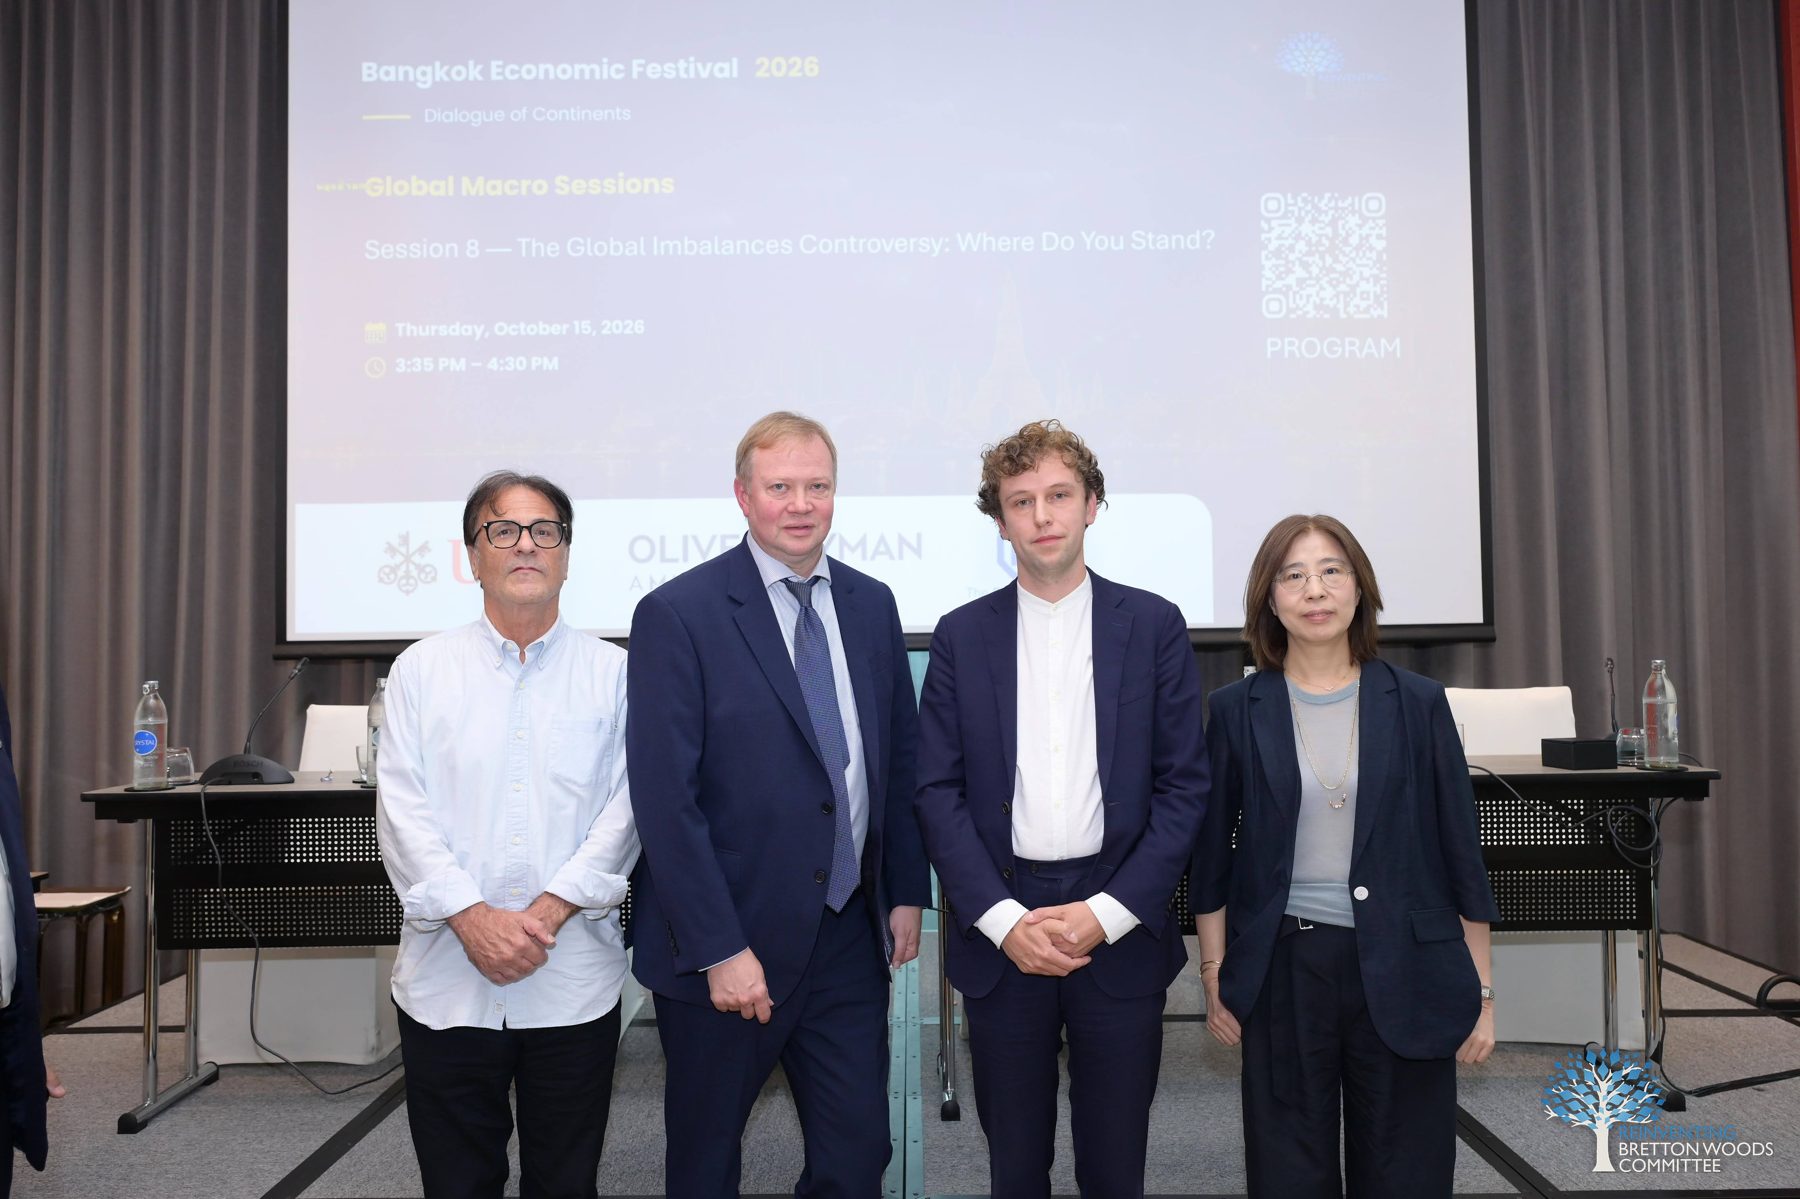
  17. Session 8 — The Global Imbalances Controversy: Where Do You Stand?

    Michael Pettis Senior Fellow, Carnegie Endowment for international Peace

    Brad Setser Senior Fellow, Council on Foreign Relations

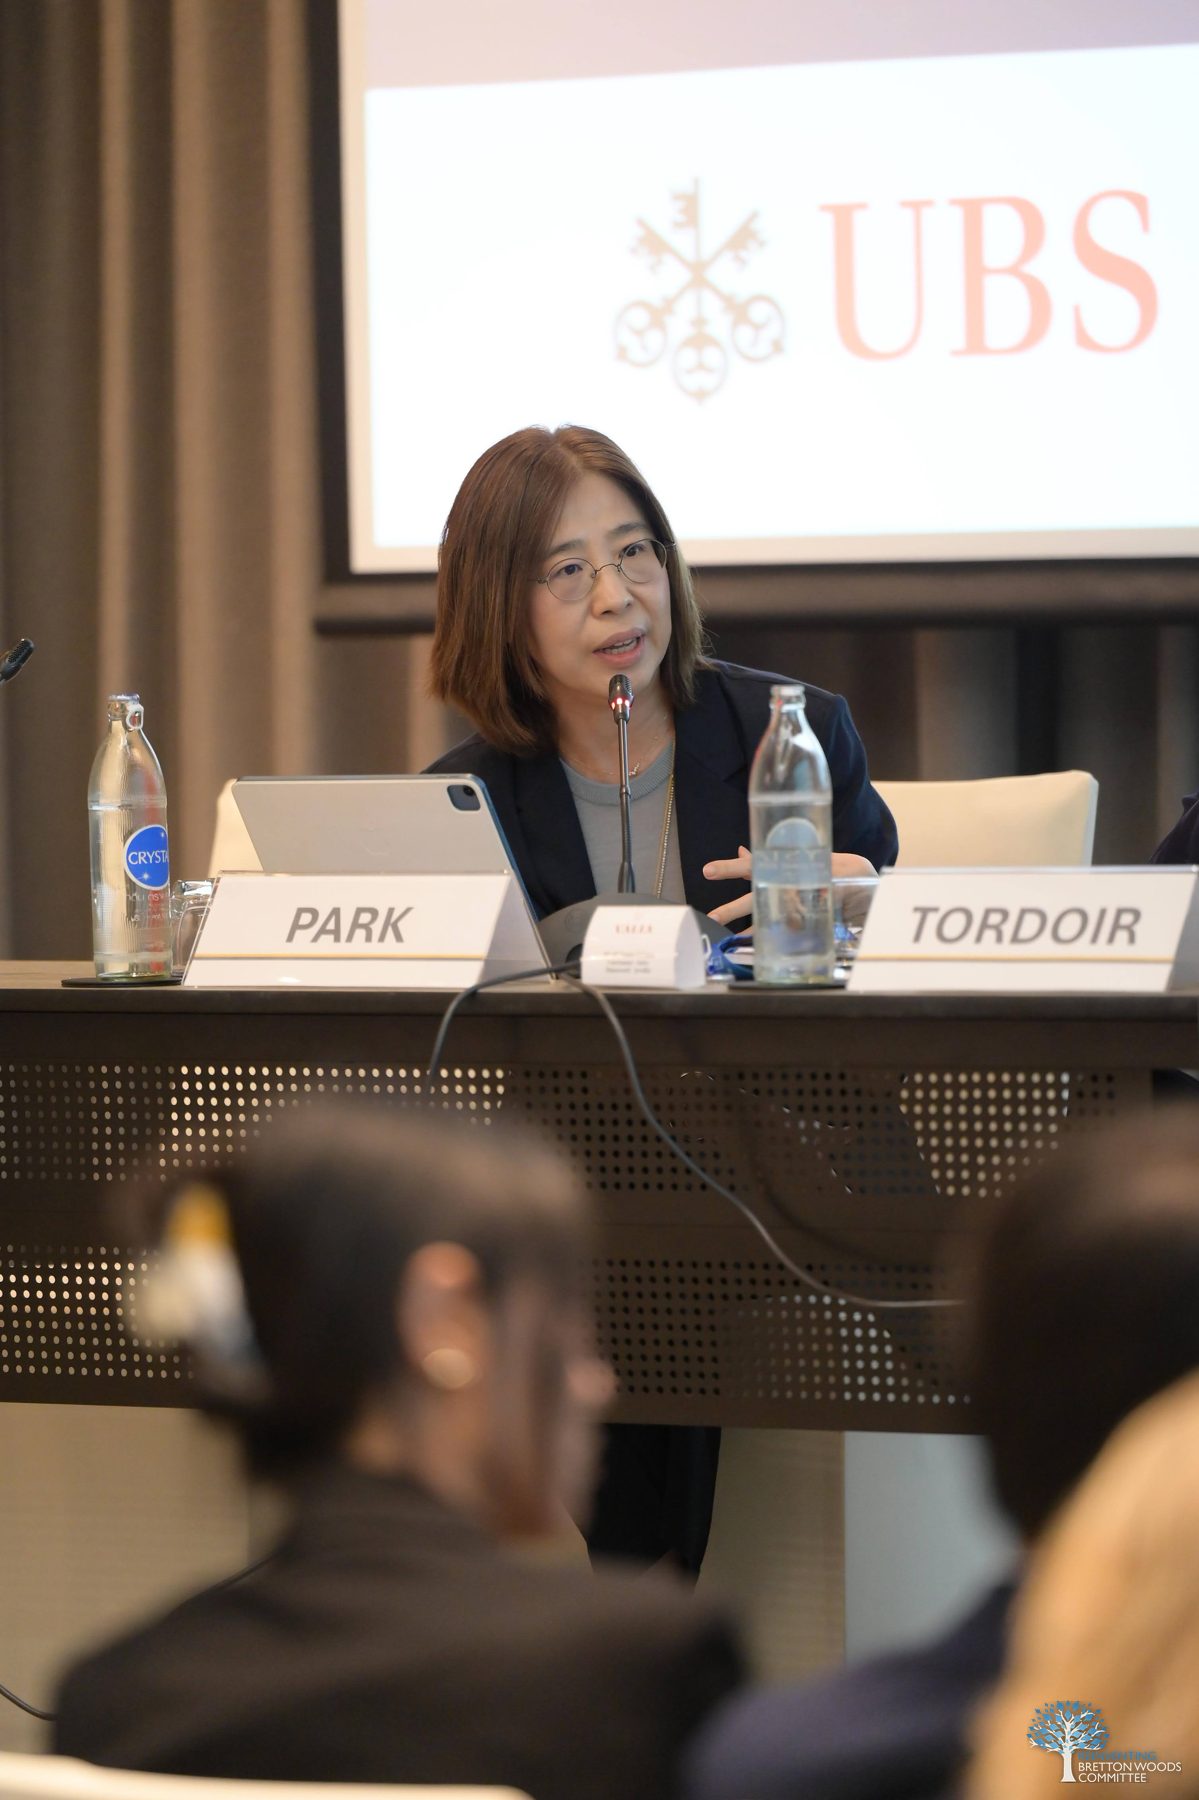
    Cynyoung

    Park Executive Director, The SEACEN Center

    Chair: Shahin Vallee —

    Senior Fellow German Council on Foreign Relations

On the Programme

Marc UzanExecutive Director, Reinventing Bretton Woods Committee
Axel WeberPresident, Center for Financial Studies
Fraziali IsmailAssistant Governor, Central Bank of Malaysia
Álvaro Santos PereiraGovernor, Central Bank of Portugal
Jonathan PingleUS Chief Economist, UBS
Klaas KnotFormer Chair, Financial Stability Board; Former President, De Nederlandsche Bank; Distinguished Visiting Fellow, PIIE
Arend KapteynGlobal Chief Economist, UBS
Michelle W. BowmanVice Chair for Supervision, Federal Reserve; Chair, FSB Standing Committee on Supervisory and Regulatory Cooperation
Kristin ForbesProfessor of Economics, MIT
Martin KocherGovernor, Austrian National Bank
Gediminas ŠimkusChairman of the Board, Bank of Lithuania and Member, ECB Governing Council
Huw PillChief Economist and Member of the Monetary Policy Committee, Bank of England
Zeno Ronald R. AbenojaDeputy Governor, BSP
Li KaiChair Professor of Finance, PBC School of Finance, Tsinghua University
Andreas DombretChairman of the Board, N26
Alfred SchipkeDirector, East Asian Institute and Professor in practice Lee Kuan Yew School of Public Policy, National University of Singapore
Vera SongweChair and Founder, Liquidity and Sustainability Facility
Dominik WehPartner, Oliver Wyman
Daniel PalotaiDeputy Governor of the Magyar Nemzeti Bank
Guillermo TolosaGovernor, Central Bank of Uruguay
Nouriel RoubiniEmeritus Professor of Economics, NYU
Rogelio MercadoAssistant Governor, Central Bank of the Philippines
Massimiliano CastelliHead, Global Sovereign Markets Strategy and Advice, UBS Asset Management
Haibin ZhuExecutive Director, Hong Kong Monetary Authority
Steven BarnettProfessor of Economics, HKU
Thomas HelblingDeputy Director, Asia and Pacific Department, IMF
Tao WangSenior Advisor, UBS
Michael PettisSenior Fellow, Carnegie Endowment for international Peace
Brad SetserSenior Fellow, Council on Foreign Relations
Cynyoung ParkExecutive Director, The SEACEN Center
Shahin ValleeSenior Fellow, German Council on Foreign Relations (Chair)

Some of What Was Said

  1. There are better uses for money than buying government bonds if you can invest into the AI boom. And governments need to wake up to that reality.
    Axel WeberPresident, Center for Financial Studies
  2. We should also recognize that so far it's been a fair weather asset class, so the credit cycle has only gone up while private credit has been growing. So we don't know how it will behave if the cycle were to turn.
    Klaas KnotFormer Chair, Financial Stability Board; Former President, De Nederlandsche Bank; Distinguished Visiting Fellow, PIIE
  3. A supervisory organization can be extremely busy and still fail to focus sufficiently on the risks that matter the most.
    Michelle W. BowmanVice Chair for Supervision, Federal Reserve; Chair, FSB Standing Committee on Supervisory and Regulatory Cooperation
  4. Over half of the decisions made by central bankers now is driven by shocks outside the control of their domestic economies and their domestic policymakers.
    Kristin ForbesProfessor of Economics, MIT
  5. I think it's easy to get sucked into a debate about trade-offs, but I think I agree very much that it's only a trade-off if you are credible. If you're not credible, you can have adverse developments in inflation and adverse developments in output.
    Huw PillChief Economist and Member of the Monetary Policy Committee, Bank of England
  6. My fundamental belief is that we cannot privatize the benefits of monetary innovation while leaving the public sector with an undefined obligation to absorb the consequences when things go wrong.
    Andreas DombretChairman of the Board, N26
  7. Emerging market local currency bonds have been less volatile than advanced market bonds in the last three years already, it's not three months, three years of having less volatility than advanced markets.
    Guillermo TolosaGovernor, Central Bank of Uruguay
  8. China had a real estate correction that should have led to a full-blown crisis anywhere else. The size of the correction and the duration, and we're still in it.
    Steven BarnettProfessor of Economics, HKU
  9. Everyone in China wants to rebalance, but they want to rebalance without a cost, and I think that's what's impossible.
    Michael PettisSenior Fellow, Carnegie Endowment for international Peace
  10. The size of China's surplus, the size of the imbalance is such that in the interest of comity, in the interest of constructive trading relations with the world, China should increase the value of its currency.
    Brad SetserSenior Fellow, Council on Foreign Relations
  11. I still see it as very much a production phase of AI. I'm still talking about AI building a supply base in terms of data centers, powers, and networks. And the adoption is still in its early days, and it will likely to come in waves.
    Fraziali IsmailAssistant Governor, Central Bank of Malaysia
  12. Dollar stablecoins are likely to reinforce the international dominance of the US dollar. But at the same time, very importantly, it also does not necessarily make the dollar-based financial system more resilient.
    Li KaiChair Professor of Finance, PBC School of Finance, Tsinghua University
  13. Last year I said tech trumps tariffs, this year I've said tech trumps oil, also said tech trumps temper tantrums too, because tech is first order and everything else is second order.
    Nouriel RoubiniEmeritus Professor of Economics, NYU
  14. We have argued that for us the external imbalance is sort of the flip side of the domestic imbalance. And that's first and foremost what needs to be addressed.
    Thomas HelblingDeputy Director, Asia and Pacific Department, IMF

In the Room

Photograph from Global Macro SessionsPhotograph from Global Macro SessionsPhotograph from Global Macro SessionsPhotograph from Global Macro SessionsPhotograph from Global Macro SessionsPhotograph from Global Macro SessionsPhotograph from Global Macro SessionsPhotograph from Global Macro SessionsPhotograph from Global Macro SessionsPhotograph from Global Macro SessionsPhotograph from Global Macro SessionsPhotograph from Global Macro SessionsPhotograph from Global Macro SessionsPhotograph from Global Macro SessionsPhotograph from Global Macro SessionsPhotograph from Global Macro SessionsPhotograph from Global Macro SessionsPhotograph from Global Macro SessionsPhotograph from Global Macro SessionsPhotograph from Global Macro SessionsPhotograph from Global Macro SessionsPhotograph from Global Macro SessionsPhotograph from Global Macro SessionsPhotograph from Global Macro SessionsPhotograph from Global Macro SessionsPhotograph from Global Macro SessionsPhotograph from Global Macro SessionsPhotograph from Global Macro SessionsPhotograph from Global Macro SessionsPhotograph from Global Macro SessionsPhotograph from Global Macro SessionsPhotograph from Global Macro SessionsPhotograph from Global Macro SessionsPhotograph from Global Macro Sessions

Day’s Video

Session livestream

Previous sessionLow-Income Countries and the IMF in a Changing World: Financing, Growth and the Path ForwardNext sessionThe Future of MDBs: More Critical than Ever